eBay (NASDAQ: EBAY) has attracted renewed interest from Wall Street following Morgan Stanley’s decision to name the online marketplace one of its top internet investments, citing the expanding contribution of live commerce to transaction growth.
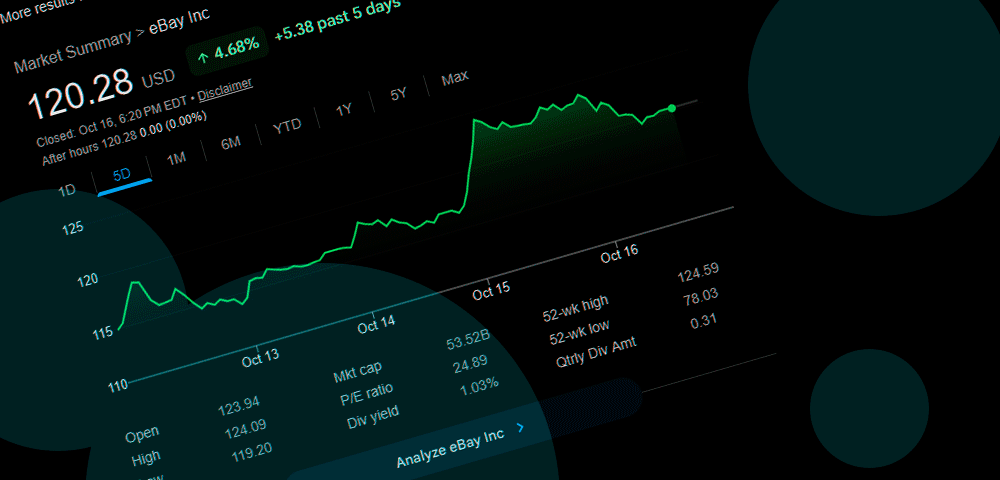
As of October 18, 2026, the latest available closing price was $120.28, recorded on October 16, when shares declined 2.14%. The stock has advanced substantially during 2026, leaving analysts divided over whether its improving growth outlook justifies further gains.
- Morgan Stanley raised its eBay price target to $132 from $127 and named the company a top internet stock, citing accelerating growth from eBay Live.
- Wall Street remains divided: 33 analysts have a consensus Hold rating and an average 12-month target of $115.24, below the current share price.
- eBay’s Q2 revenue increased 15% to $3.13 bn, while gross merchandise volume reached $22.4 bn. Third-quarter earnings are scheduled for October 28.
According to MarketBeat, the average 12-month price target across 33 analysts stands at $115.24, implying 4.19% downside from the latest close. The consensus rating is Hold, comprising 15 positive recommendations, 16 Hold ratings and two Sell ratings.
Individual forecasts range from $75 to $145 per share, reflecting considerable disagreement about eBay’s growth potential and valuation.
Morgan Stanley analyst Nathan Feather raised his price target from $127 to $132 on October 12, maintaining an Overweight recommendation. The revised forecast implies approximately 9.7% upside from the October 16 closing price.
Morgan Stanley’s investment thesis centers on eBay Live, the company’s livestream shopping platform. The bank estimates that live commerce accounts for more than 40% of eBay’s incremental merchandise volume growth and could contribute approximately four percentage points to annual GMV growth through 2030.
The firm expects the development to support medium to high single-digit GMV growth, exceeding broader market expectations.
eBay stock price targets from leading analysts
Several other brokerages remain positive about eBay’s prospects. Wedbush maintains an Outperform rating with a $137 target, implying approximately 13.9% upside. Needham has a Buy rating and a $135 target, while Benchmark’s Buy recommendation carries a $134 forecast.
Piper Sandler maintains an Overweight rating with a $133 target. Citigroup has a Buy rating and a $130 target, while Baird’s latest reported target is $126.
The bearish forecasts are considerably lower. Wells Fargo analyst Ken Gawrelski reduced his target from $92 to $91 on October 12, maintaining an Underweight rating. Jefferies analyst John Colantuoni lowered his forecast from $80 to $75 in September, retaining an Underperform recommendation.
The gap between bullish and bearish forecasts indicates that analysts disagree over how much sustainable revenue and earnings growth eBay can generate from its marketplace investments.
eBay earnings and revenue growth support the bullish case
eBay reported second-quarter 2026 revenue of $3.13 bn, an increase of 15% year over year. Gross merchandise volume also rose 15% to $22.4 bn. Adjusted earnings reached $1.60 per diluted share, while GAAP earnings were $1.21 per share.
The company’s adjusted operating margin was 28.5%, and free cash flow from continuing operations totaled $326 mn.
eBay returned $448 mn to shareholders during the quarter, including $310 mn in share repurchases and $138 mn in dividends.
The company also completed its approximately $1.2 bn acquisition of secondhand fashion marketplace Depop in July, extending its exposure to younger consumers and the resale market.
Management expects third-quarter revenue of $3.07 bn to $3.12 bn and GMV of $22 bn to $22.4 bn. Adjusted earnings guidance stands at $1.36 to $1.42 per share. Analysts expect approximately $3.11 bn in quarterly revenue and $1.41 in adjusted earnings per share.
GameStop’s $125 acquisition proposal remains a valuation factor
Corporate activity presents another consideration for eBay shareholders. In May 2026, GameStop made an unsolicited proposal to acquire eBay for $125 per share, valuing the company at approximately $55.5 bn. The proposed consideration comprised 50% cash and 50% GameStop shares.
eBay’s board rejected the non-binding offer on May 12, citing concerns about financing, operational risks, leverage and the proposed transaction’s attractiveness to shareholders.
GameStop subsequently increased its investment in eBay, with its reported ownership approaching 10%.
At the October 16 closing price, the original $125 proposal represented a premium of approximately 3.9%. However, the rejected offer is not a binding transaction and should not be treated as an assured valuation floor.
eBay stock outlook for 2026 and 2027
eBay’s next earnings release on October 28 will provide a clearer test of Morgan Stanley’s growth assumptions, particularly the contribution of eBay Live to marketplace activity.
Investors will focus on GMV growth, the integration of Depop, operating margins and the company’s ability to maintain strong cash generation.
Morgan Stanley’s $132 forecast suggests further upside if live commerce delivers sustained growth. Other bullish analysts see potential valuations above $130.
The broader consensus presents a more cautious assessment. With shares trading above the average Wall Street target, continued appreciation will depend on earnings performance exceeding expectations rather than simply maintaining current growth rates.
For investors, the central question is whether eBay can convert stronger marketplace activity into durable earnings growth sufficient to support its higher valuation.