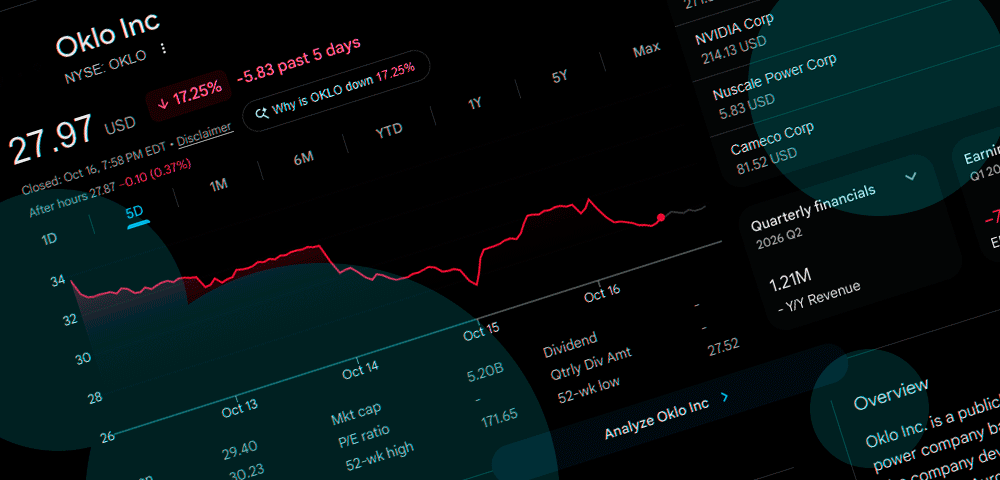
Oklo (NYSE: OKLO) enters the final quarter of 2026 under considerable selling pressure as investors reassess the valuation of advanced nuclear energy companies and their ability to finance commercial reactor development.
Shares closed at $27.97 on October 16, declining 6.8% during the session. The stock has fallen approximately 61% year to date and trades close to its 52-week low of $27.52, compared with a high of $170.
- Oklo shares closed at $27.97 on October 16, down 6.8%, bringing their year-to-date decline to approximately 61%. The average analyst price target of $75.38 implies nearly 170% potential upside.
- UBS reduced its target to $41, while Bank of America maintained $80 and Canaccord Genuity forecast $100. Analyst recommendations remain divided over commercialization and valuation risks.
- Oklo established another $1 bn equity offering program after selling nearly 18 mn shares through its previous arrangement, increasing potential shareholder dilution as reactor development costs rise.
The decline has created a substantial gap between Oklo’s market valuation and Wall Street’s longer-term earnings expectations.
According to S&P Global Market Intelligence data covering 23 analysts, the average 12-month price target stands at $75.38, representing approximately 169.5% upside from the latest closing price. The median forecast is $74.50, with individual targets ranging from $14 to $130.
The consensus remains Buy, although several investment banks have reduced their forecasts as attention shifts toward financing requirements, regulatory approvals and project execution.
Oklo stock forecast: Latest Wall Street analyst ratings
UBS analyst Jon Windham lowered his price target from $55 to $41 on September 25, maintaining a Neutral recommendation. The revised forecast implies approximately 47% upside from the October 16 closing price.
Piper Sandler analyst Dimple Gosai initiated coverage with an Overweight rating and a $55 target in September, reiterating the recommendation on October 1.
- Bank of America Securities maintained a Buy rating and an $80 target in its latest available October assessment.
- Citigroup analyst Vikram Bagri reduced his forecast from $76 to $57.50 in August while maintaining a Neutral rating.
- Canaccord Genuity analyst George Gianarikas lowered his target from $125 to $100 but retained a Buy recommendation. Barclays reduced its target from $82 to $76 while maintaining Overweight.
- Other positive forecasts include Wedbush’s $110 target and H.C. Wainwright’s $90 target.
The differences between these estimates reflect uncertainty over when Oklo will begin generating substantial electricity revenue and how much additional financing commercial deployment will require.
Consensus figures also vary by provider. MarketBeat reports an average target of $82.44, compared with S&P Global’s $75.38, because of differences in analyst coverage and aggregation methods.
$1 bn share offering raises dilution concerns
Oklo’s financing strategy has become an important factor in its stock performance. On September 11, 2026, the company established an at-the-market equity offering program allowing it to sell up to $1 bn in additional common shares.
The arrangement followed the termination of a previous $1 bn offering established in May. Under that program, Oklo sold 17,971,448 shares for approximately $1 bn in gross proceeds.
The new authorization does not mean all $1 bn of additional shares have already been issued. Nevertheless, lower share prices increase the number of shares required to raise a given amount of capital.
At $27.97 per share, raising the full $1 bn would require approximately 35.8 mn shares, assuming a constant selling price and excluding transaction costs. That is nearly twice the number issued through the previous program.
Oklo had approximately 122.1 mn shares outstanding when it completed its SPAC merger in May 2024. By August 4, 2026, its reported Class A share count had reached approximately 186 mn.
Further equity issuance would reduce existing investors’ proportional ownership unless offset by other changes in the share count.
Oklo holds $3 bn in cash and securities but faces rising spending
Oklo reported approximately $3.01 bn in cash, cash equivalents and marketable debt securities at June 30, 2026, providing substantial liquidity for its development program.
The company recorded $1.21 mn in second-quarter revenue, primarily from engineering, consulting and related services following acquisitions. It has not yet generated commercial electricity sales from its planned Aurora reactors.
For the first half of 2026, Oklo reported a net loss of $81.6 mn and operating cash outflows of $65.5 mn.
Management expects full-year operating cash use of $120 mn to $150 mn, alongside capital expenditure of $400 mn to $500 mn.
The spending reflects ongoing work on reactor development, nuclear fuel infrastructure and other planned facilities.
Oklo is pursuing commercial deployment of its Aurora fast-fission reactors, targeting customers seeking reliable electricity supplies, including AI data centers.
An agreement with Meta Platforms supports plans for a nuclear energy campus of up to 1.2 gigawatts in Pike County, Ohio. The agreement provides a mechanism for advance power payments and development funding, including nuclear fuel procurement.
The project offers a potential route toward commercial scale, but reactor construction, licensing and commissioning remain subject to execution and regulatory requirements.
Oklo stock outlook for 2027
The investment case for Oklo depends less on current earnings than on the company’s ability to turn its reactor technology and customer agreements into operating power assets.
Demand for electricity from AI infrastructure remains a potential growth driver, but that demand does not eliminate construction, licensing or financing risks.
Further dilution could also limit the benefit existing shareholders receive from future business growth.
Oklo’s average analyst target of $75.38 points to substantial potential appreciation over the next 12 months. Yet the wide range of forecasts and recent target reductions indicate limited agreement about the company’s near-term valuation.
Investors will be watching regulatory milestones, binding power agreements, capital spending, liquidity and further equity issuance.
Oklo has sufficient reported financial resources to continue development in the near term, but its longer-term valuation depends on delivering commercial nuclear generation at costs and timelines that justify continued investment.