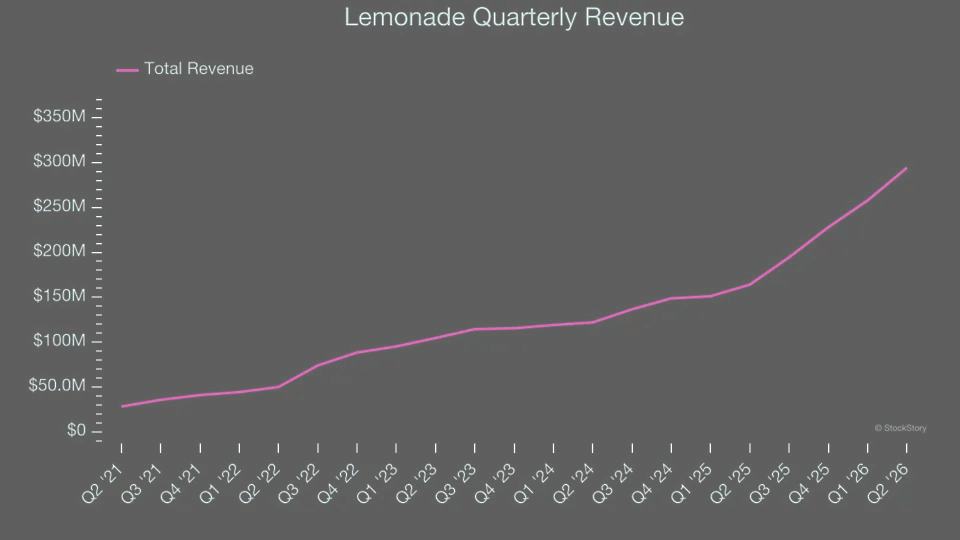
- Lemonade’s Q2 2026 revenue rose 79.4% year over year to $294.4 mn, beating Wall Street estimates by 1.2%.
- Net premiums earned increased 124% year over year to $252 mn, showing continued growth in Lemonade’s insurance operations.
- Despite the revenue beat, LMND shares fell 15.1% after results as investors reacted to weaker second-half 2026 guidance.
Insurtech Lemonade reported second-quarter 2026 revenue above Wall Street expectations, with sales rising 79.4% year over year to $294.4 mn.
The New York-listed company also gave third-quarter revenue guidance of $324.5 mn at the midpoint, slightly above analyst estimates. Its GAAP loss came in at $0.56 per share, matching consensus forecasts.
Net premiums earned reached $252 mn, above analyst expectations of $246.4 mn. The figure rose 124% from the same period last year and beat estimates by 2.3%.
Revenue reached $294.4 mn, ahead of Wall Street’s $290.9 mn forecast. The beat was modest at 1.2%, but the pace of growth remained far above the broader insurance sector.
Lemonade reported a pre-tax loss of $41.8 mn, equal to a negative 14.2% margin. Full-year revenue guidance stood at $1.22 bn at the midpoint, broadly in line with analyst expectations.
The company had a market capitalization of $4.77 bn after the results.
Lemonade sells homeowners, renters, pet, car and life insurance through an AI-powered digital platform. Its model also includes a giveback structure, where unused premiums go to charities selected by policyholders.
Insurers usually generate revenue through earned premiums, investment income and fees. Premiums remain Lemonade’s main revenue source. Over the past five years, net premiums earned made up 73.9% of total revenue.
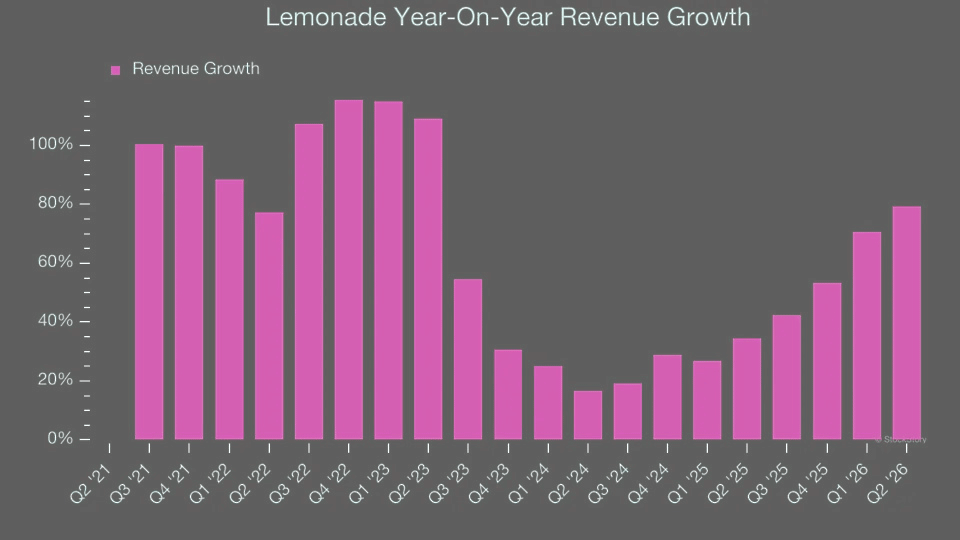
According to StockStory, Lemonade’s revenue grew at a 61% annualized rate over the past five years. That pace sits well above the insurance industry average and suggests the company’s digital insurance products continue to gain customers. The recent growth curve has slowed compared with the longer trend. Over the past two years, Lemonade’s annualized revenue growth reached 43.9%. That isn’t weak. It simply trails the five-year rate.
The second quarter still delivered a strong top-line result. Revenue rose 79.4% year over year, and management guided for 66.8% sales growth in the next quarter.
Net premiums earned matter more to insurance investors than fee income or investment income, because they show how the underwriting operation itself is scaling. Investment returns shift with markets. Fee income moves differently.
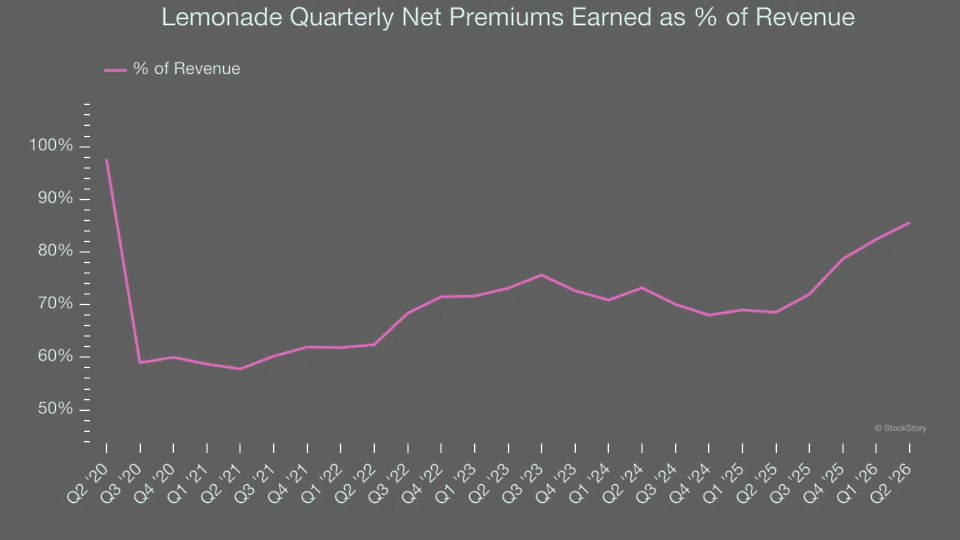
Lemonade’s net premiums earned rose at a 71.5% annualized rate over the past five years. That growth ran faster than total revenue, which points to the company’s insurance book as the main driver. Over the past two years, net premiums earned grew 50.9% annually. The deceleration matches the broader cooling in revenue growth, though it still shows strong demand for Lemonade’s policies.
In Q2, Lemonade produced $252 mn in net premiums earned. That figure rose 124% year over year and came in ahead of Wall Street consensus estimates.
The quarter gave investors strong premium growth, a revenue beat and third-quarter guidance above expectations. The issue sat elsewhere. Guidance for the second half of 2026 came in below market expectations.
The market reaction was harsh. Lemonade shares dropped 15.1% to $52.75 shortly after the report, signaling investors wanted a cleaner beat and stronger forward numbers.