Nebius Group (NASDAQ: NBIS) shares rallied sharply on November 11, 2026, ahead of the company’s third-quarter earnings release scheduled for November 12.
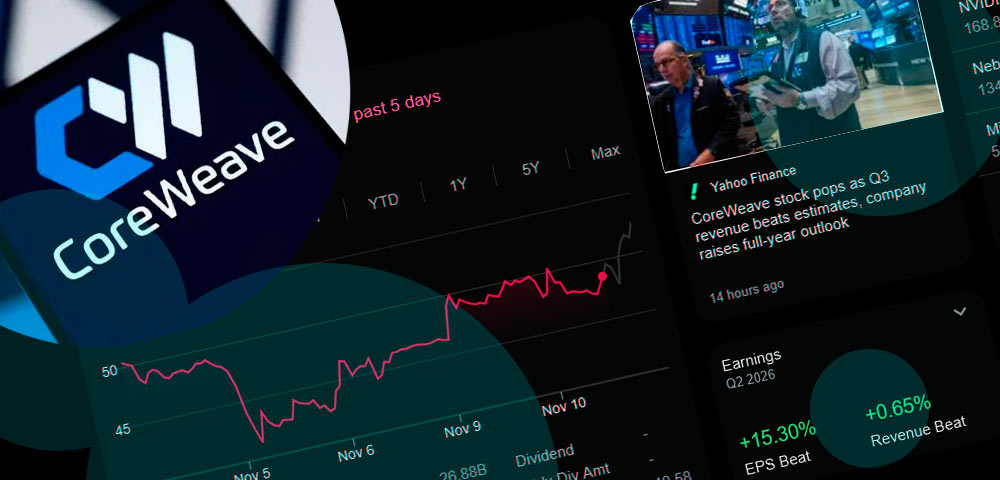
The recovery followed stronger-than-expected results from CoreWeave, which reported third-quarter revenue of $3.66 bn, up 168%, and a revenue backlog of approximately $132.5 bn.
- Nebius shares rebounded 12-15% in November 11 premarket trading, reaching approximately $150-154 after closing at $134 on November 10. Strong earnings from CoreWeave helped restore confidence in AI infrastructure stocks.
- Wall Street expects Q3 revenue of approximately $907 mn, up 521% year over year. However, analysts anticipate a quarterly loss of roughly $0.60-0.70 per share as infrastructure investment accelerates.
- Investment bank price targets range from $144 to $399, reflecting sharply different expectations for Nebius’s growth, financing requirements and profitability. The broader analyst consensus stands near $297.
CoreWeave’s results strengthened expectations that demand for AI computing capacity remains robust despite concerns about infrastructure financing, high debt levels and the profitability of large-scale data center investments.
For Nebius, the immediate question is whether rapid revenue growth can justify its capital requirements and support the company’s valuation.
Nebius Stock Forecast: Investment Bank Price Targets
Wall Street remains predominantly positive on NBIS despite the stock’s substantial decline from its August highs.
Across 13 analyst ratings, the consensus includes nine Buy recommendations, three Holds and one Sell. The average 12-month price target is approximately $296.73, although estimates differ between market-data providers.
Latest Investment Bank Forecasts for NBIS
| Investment Bank | Rating | 12-Month Price Target | Latest Update |
|---|---|---|---|
| Morgan Stanley | Equal Weight | $144 | August 2026 |
| Piper Sandler | Neutral | $185 | October 21 |
| Citigroup | Buy | $265 | November 4 |
| Bank of America | Buy | $310 | October 22 |
| Goldman Sachs | Buy | $328 | August 25 |
| Exane BNP Paribas | Outperform | $399 | September 24 |
The difference between bullish and cautious forecasts is substantial.
Citigroup maintained its Buy rating but lowered its target from $324 to $265 in early November. The revision indicates that expectations have become more conservative even among banks maintaining a positive view of Nebius.
Piper Sandler also reduced its target, from $237 to $185, while retaining a Neutral recommendation.
By contrast, Bank of America and Goldman Sachs maintain substantially higher valuations, reflecting confidence in the company’s longer-term AI infrastructure expansion.
Morgan Stanley’s $144 target represents a more cautious assessment of the balance between growth potential and execution risk.
At a premarket share price near $150, the broader $296.73 consensus implies approximately 98% potential appreciation over 12 months. That figure reflects analyst expectations, not a guaranteed return.
Nebius Q3 2026 Earnings Forecast
Nebius will publish its third-quarter results before the U.S. market opens on November 12. Current expectations indicate another quarter of exceptional revenue growth.
| Financial Indicator | Q3 2026 Expectations |
|---|---|
| Revenue | $907 mn |
| Revenue growth YoY | +521% |
| Revenue Q3 2025 | $146.1 mn |
| Revenue Q2 2026 | $582.3 mn |
| Expected sequential revenue growth | 56% |
| Forecast EPS | Loss of $0.60-0.70 |
The expected revenue increase primarily reflects the expansion of AI computing capacity and growing demand from enterprise customers and hyperscalers. However, headline revenue growth is unlikely to determine the stock’s direction on its own.
Investors will focus on whether Nebius is bringing data center capacity online according to schedule, securing sufficient financing and translating long-term contracts into recognized revenue.
The company’s outlook for 2027 could therefore have greater influence on its valuation than a modest earnings beat.
AI Infrastructure Contracts Support Long-Term Growth
Nebius has established a significant portfolio of AI infrastructure commitments. In March 2026, the company announced a five-year agreement with Meta covering $12 bn of dedicated computing capacity, with deliveries scheduled to begin in early 2027.
The arrangement also includes commitments for up to $15 bn of additional capacity, bringing its potential total value to approximately $27 bn.
The additional capacity is intended primarily for third-party AI cloud customers, with Meta committed to purchasing remaining available capacity under the agreed terms.
The agreements nevertheless provide greater visibility into future demand and help support financing for new data centers and NVIDIA-powered computing infrastructure.
Nebius has also indicated that it holds more than $40 bn in long-term customer commitments.
Financing Remains the Biggest Valuation Risk
Rapid expansion requires substantial investment in GPUs, power infrastructure, cooling systems and data center construction.
In October, Nebius secured a $3.5 bn senior secured financing facility from Citi to support infrastructure development and GPU procurement. The facility has an initial maturity of 364 days, with interest starting at Term SOFR plus 2.75%.
Earlier, in August, the company completed an approximately $5.75 bn convertible senior notes offering.
These transactions demonstrate Nebius’s access to substantial capital, but they also underline the scale of its funding requirements.
Debt financing increases interest expenses, while convertible securities can create potential shareholder dilution. A prolonged period of elevated U.S. interest rates would make future expansion more expensive.
Microsoft-related uncertainty adds another risk. Reports that the technology group has increased scrutiny of certain AI infrastructure projects have raised questions about delivery schedules and future customer commitments.
Such scrutiny should not be confused with confirmation that existing contracts will be terminated.
NBIS Stock Outlook for 2027
Nebius’s medium-term outlook depends on three developments.
- First, capacity delivery. Successful commissioning of new facilities would support revenue growth and improve confidence in the company’s ability to fulfill major customer agreements.
- Second, financing costs. Access to capital on manageable terms would reduce pressure on profitability and shareholder dilution.
- Third, utilization and margins. Higher demand and stronger GPU pricing could improve returns on infrastructure investment, provided operating costs remain under control.
The bullish case assumes that Nebius delivers its planned expansion, converts customer commitments into revenue and demonstrates improving operating economics. Under those conditions, the higher investment bank targets of $265–328 become more defensible.
The bearish case involves project delays, higher financing expenses, weaker utilization or changes in major customer spending plans. These outcomes could keep the stock closer to the more cautious $144–185 valuation range.
Nebius Stock Forecast: What Matters Next?
The November 12 earnings release is the immediate catalyst for NBIS.
Revenue approaching $907 mn would confirm rapid business expansion, but the market is likely to place greater weight on management’s capacity deployment schedule, financing strategy and 2027 outlook.
Wall Street’s predominantly bullish forecasts indicate considerable perceived upside, but the wide spread between price targets shows that execution and financing risks remain central to the stock’s valuation.