- California wildfire insurance crisis drives proposed reforms
- How Jane Kim’s state-run wildfire insurance program would work
- California state insurance plan could require $25 bn in capital
- California Earthquake Authority offers a potential comparison
- Wildfire claims handling remains an unresolved challenge
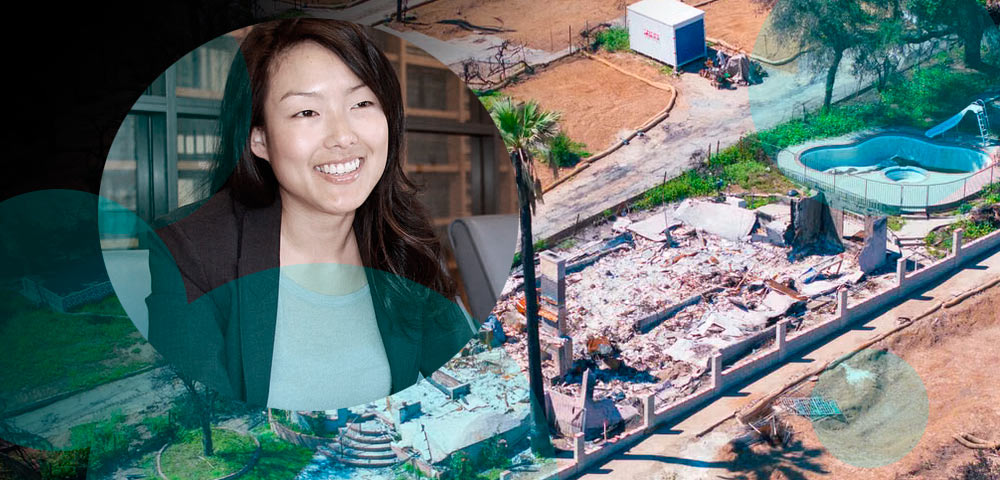
California’s incoming insurance commissioner, Jane Kim, is proposing a government-operated wildfire insurance program that would transfer catastrophe exposure from private insurers to a statewide insurance pool funded by homeowners.
Kim, a former San Francisco supervisor who narrowly defeated Democratic state Sen. Ben Allen, made the proposal a central part of her campaign as California struggles with rising home insurance costs, insurer withdrawals and increasing wildfire exposure.
Her Natural Disaster Insurance for All initiative would establish mandatory wildfire coverage for existing homes while allowing commercial insurers to continue underwriting other property risks.
- California’s newly elected insurance commissioner Jane Kim proposes mandatory, state-run wildfire coverage to address rising premiums and declining insurance availability.
- California FAIR Plan residential policies have more than doubled to 677,000 since 2022, following insurer withdrawals and catastrophic wildfire losses.
- A state study estimates the proposed insurance system could require $25 bn in startup capital, potentially falling to $6 bn with substantial reinsurance.
Kim argues that removing profit margins and certain operating expenses from wildfire insurance, while prioritizing risk reduction, could improve affordability and availability.
We understand that this is a bold proposal, and I think that the crisis demands a bold proposal. The current framework is failing, and if you talk to your everyday Californian, they don’t believe the current system is working.
Jane Kim
The proposal remains preliminary. Its financing structure, claims administration arrangements and implementation requirements have not been finalized.
California wildfire insurance crisis drives proposed reforms
California’s home insurance market has faced increasing pressure following a series of destructive wildfires over the past decade.
The January 7, 2025, fires in Pacific Palisades and Altadena damaged or destroyed more than 16,000 structures, adding to insurers’ catastrophe losses and prompting further scrutiny of underwriting practices.
Private carriers have reduced their exposure in wildfire-prone communities, declined renewals and increased premiums, although California’s statewide average home insurance costs remain close to the national average under some comparisons.
These restrictions have pushed more homeowners toward the California FAIR Plan, the industry’s privately operated insurer of last resort.
Its residential policy count has more than doubled since 2022, reaching approximately 677,000.
Following roughly $4 bn in losses associated with the January 2025 fires, the FAIR Plan imposed assessments that resulted in surcharges for residential insurance policyholders across California.
The growing dependence on the FAIR Plan has intensified debate over whether the existing private insurance structure can provide affordable protection against increasingly expensive natural catastrophes.
How Jane Kim’s state-run wildfire insurance program would work
Kim’s proposal would separate major wildfire losses from conventional homeowners insurance.
Under a policy framework released by her campaign in October, private insurers would continue offering coverage for water damage, wind, theft, liability and ordinary residential fires.
Large wildfire losses would instead be covered by a state-managed program. Commercial carriers could sell the government-backed wildfire protection alongside their existing homeowners policies, but the state program would retain the associated risk and finance eligible claims.
Coverage would be mandatory, creating a broad insurance pool across California’s existing housing stock.
The proposed premium structure would have two components.
- The first would reflect a property’s individual wildfire exposure and estimated rebuilding costs, providing sufficient revenue to cover expected losses during a typical fire year.
- A second, capped charge would accumulate capital to help finance losses during particularly destructive wildfire seasons.
The program would cover the cost of fully rebuilding a typical California home, although the policy brief does not specify a monetary limit.
Owners of more expensive properties could purchase supplementary coverage from commercial insurers.
According to Kim’s policy outline, the program would prioritize ordinary homeowners rather than subsidizing the reconstruction of luxury properties.
All existing homes would qualify, while eligibility rules for newly constructed properties would require further consideration of wildfire exposure and mitigation measures.
California state insurance plan could require $25 bn in capital
Financing represents one of the largest unresolved issues. A natural catastrophe resilience study commissioned by Gov. Gavin Newsom examined a similar state wildfire insurance approach and estimated that approximately $25 bn in startup capital could be necessary to prepare for a severe wildfire season.
Potential financing mechanisms include bond issuance, assessments and catastrophe reinsurance. The study found that substantial reinsurance protection could reduce the initial capital requirement to approximately $6 bn.
That approach would introduce additional costs, however, potentially increasing aggregate homeowner insurance premiums from around $18 bn to more than $20 bn.
Reinsurance would transfer some catastrophe exposure to external providers, helping the state manage extreme losses without retaining the full amount of capital itself. Its pricing and availability would nevertheless affect the cost of coverage.
Kim maintains that a public insurance model could eventually lower premiums by directing greater resources toward wildfire prevention and reducing expected losses.
California Earthquake Authority offers a potential comparison
California already operates a state-established catastrophe insurance program through the CEA, created in 1996 following the 1994 Northridge earthquake. The authority was established after private insurers became reluctant to offer earthquake coverage.
Initially capitalized by participating insurers, the CEA now provides coverage for fewer than 1 mn policies, primarily covering homes, condominiums, rental properties and mobile homes.
Its earthquake insurance deductibles range from 5% to 25%, with premiums varying according to property age, construction characteristics, location and deductible selection.
Annual premiums for homeowners can exceed $2,000, according to estimates cited in the discussion of Kim’s proposal.
The CEA demonstrates how a government-established catastrophe insurance pool can still face affordability problems.
CEA said the authority has reduced its reinsurance purchases in recent years, while premiums reflect the need to maintain sufficient claims-paying capacity for an earthquake potentially more destructive than the 1906 San Francisco event.
Kim rejects a direct comparison between the two programs. She argues that earthquake insurance is voluntary and serves a relatively small policyholder base, whereas mandatory wildfire protection would distribute risk across millions of California homeowners.
The size of the insurance pool is therefore central to her proposed financing model.
Wildfire claims handling remains an unresolved challenge
Another major question concerns who would administer claims after a catastrophe. The proposal leaves open whether private insurers would handle wildfire claims on behalf of the state or whether the new program would employ its own claims adjusters.
Claims administration has become particularly contentious following the January 2025 fires.
The California Department of Insurance and Los Angeles County are investigating claims-handling practices at several home insurers, including State Farm General, following complaints involving delays, underpayments and denials.
Chuck Nyce, an insurance professor at Florida State University’s Herbert Wertheim College of Business, said operating an independent catastrophe claims system could create substantial fixed costs.
A state program would need access to enough experienced adjusters to respond to a major disaster, even though those specialists might be required only intermittently.
Large private insurers already employ claims personnel who handle routine cases and can be reassigned during catastrophe events.
A state-run system could instead need to maintain contractual arrangements with adjusters throughout the year to ensure sufficient capacity when major losses occur.
Having private insurers administer wildfire claims financed by the state could create a different problem.
Insurers handling claims without retaining the underlying financial risk might have limited incentives to control settlement costs. Such arrangements would require safeguards to prevent inefficient claims payments while ensuring appropriate treatment of policyholders.
The program would also need to establish how wildfire mitigation affects premiums and how insurance protection is maintained following exceptionally destructive fire seasons.
For California homeowners, the principal unresolved question is whether a mandatory public wildfire insurance pool could provide broader coverage at lower cost while retaining enough capital to pay claims after another catastrophe comparable to the 2025 fires.