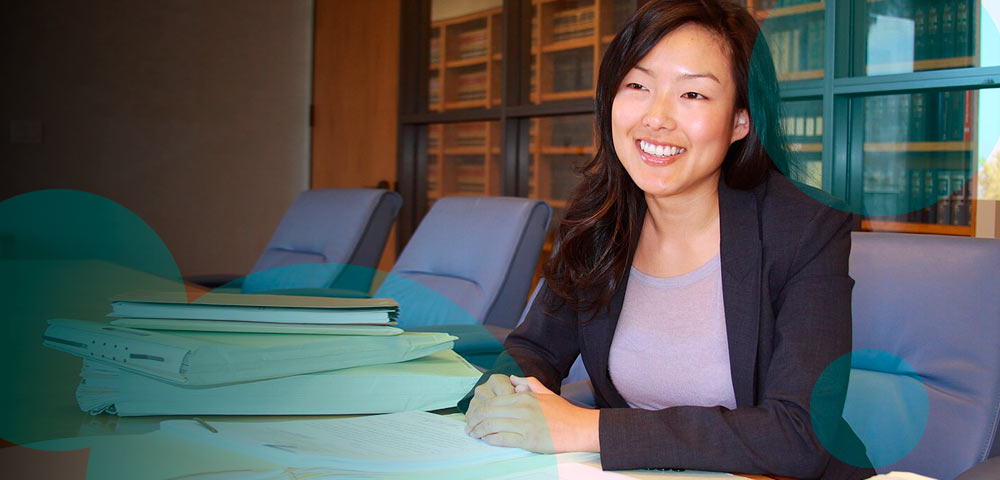
Jane Kim declared victory in California’s insurance commissioner election, holding a substantial lead over state Sen. Ben Allen in a closely watched contest over the future of the state’s troubled insurance market.
Kim, who campaigned on lowering premiums and fundamentally changing how disaster insurance operates, announced her victory as election officials continued counting ballots from Tuesday’s statewide vote.
- Former San Francisco Supervisor Jane Kim declared victory in California’s insurance commissioner election, leading state Sen. Ben Allen by approximately five percentage points.
- With nearly 65% of estimated votes counted, Kim held 52.6% against Allen’s 47.3%, although the Associated Press had not formally called the race.
- Kim proposes a state-backed disaster insurance system aimed at reducing homeowners’ dependence on private insurers, a plan requiring legislative approval.
According to Associated Press figures published Friday morning, Kim received 52.6% of the vote, representing approximately 4.01 mn ballots, compared with Allen’s 47.3%, or 3.60 mn votes.
The figures were based on an estimated 64.7% of votes counted as of 10:26 a.m. Pacific Time on November 6.
Although Kim’s advantage had widened since election night, the Associated Press had not formally called the race. Allen’s campaign had also not issued a public concession.
However, Allen reportedly contacted Kim on Friday to congratulate her on the result.
Jane Kim promises major changes to California’s insurance market
Kim announced her victory during an appearance near Dolores Park in San Francisco, thanking labor organizations and progressive groups that supported her campaign.
Her supporters included the California Federation of Labor Unions, Service Employees International Union-California and the Working Families Party, which Kim previously led in the state.
She also received endorsements from US Sen. Bernie Sanders and California State Controller Malia Cohen.
Kim presented the election results as a mandate to challenge insurance industry practices that she argues have made coverage increasingly unaffordable and difficult to obtain.
During the campaign, she criticized insurers over rising premiums, canceled policies and disputes involving claims payments. She argued that insurance should primarily provide financial protection against unexpected losses rather than maximize returns for insurance companies.
The former supervisor said her administration would prioritize making policies more affordable, improving access to coverage and strengthening consumer protections.
Kim also indicated that her team had begun preparing for a possible transition into office. If elected, she would succeed Ricardo Lara, who is leaving the position because of term limits.
Kim proposes state-backed wildfire insurance system
One of Kim’s central campaign proposals involves establishing a public-private disaster insurance system that would provide a basic level of protection for California homeowners.
Under her proposal, a state-backed fund would cover eligible disaster losses up to the average value of a California home. Homeowners seeking protection above that amount would obtain additional coverage from private insurers.
The fund would be financed through a surcharge on homeowners’ insurance policies, creating a shared mechanism for covering disaster-related losses.
Kim argues that this approach could make essential insurance protection more widely available while reducing dependence on private companies operating in increasingly high-risk areas.
The proposal would represent a significant departure from California’s existing insurance framework, which relies primarily on private carriers supplemented by the FAIR Plan, the state’s insurer of last resort.
However, the commissioner would not have the authority to establish such a system independently. Implementing the proposal would require legislation and approval from the governor.
Ben Allen focused on wildfire prevention and regulatory reform
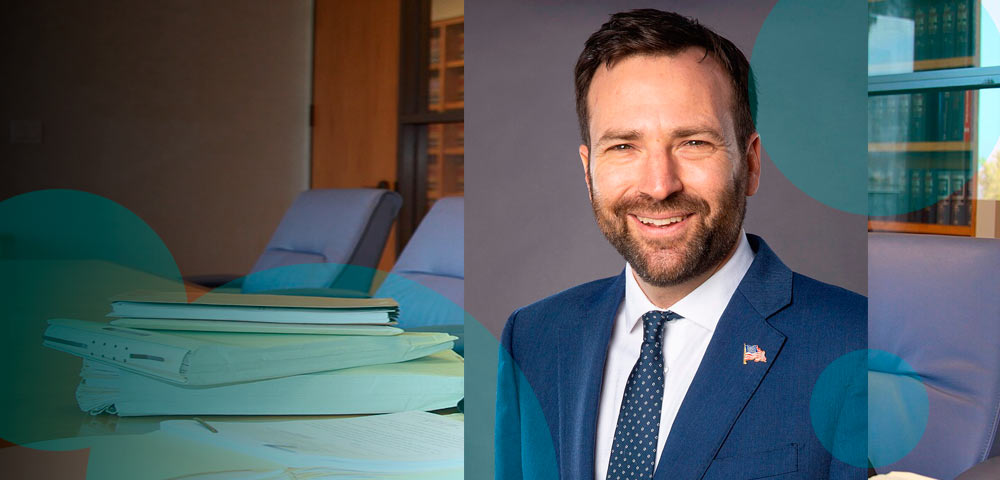
Allen, a Democratic state senator representing the Santa Monica area, offered a different approach to addressing the state’s insurance challenges.
Rather than replacing substantial portions of the private insurance market, he proposed working with insurers, communities and government agencies to reduce the risks that contribute to higher premiums.
His platform emphasized wildfire prevention, investment in property protection and improvements to the California Department of Insurance.
Allen supported expanding public assistance to help homeowners and businesses make buildings more resistant to fires. He also proposed hiring additional department staff, improving customer service and making regulatory processes more responsive to policyholders.
Allen said his interest in the office was influenced by his experience helping constituents navigate insurance problems following devastating wildfires in the Los Angeles area.
Throughout the campaign, Allen argued that reducing the underlying risk of catastrophic losses would be essential to improving insurance affordability and encouraging carriers to offer coverage.
Although both candidates are Democrats, their proposals reflected substantially different views about the role of government in California’s insurance market.
California insurance crisis dominates election
The election took place against a backdrop of rising insurance costs and declining coverage availability across California.
In recent years, several major insurers have restricted new homeowners’ policies, declined renewals or reduced their exposure to areas considered vulnerable to wildfires.
Those decisions have pushed more residents toward the California FAIR Plan, which provides limited property insurance when coverage is unavailable through traditional insurers.
The growing reliance on the FAIR Plan has raised concerns about the sustainability of California’s insurance system and the financial risks associated with future catastrophes.
Residents have also faced substantial premium increases, adding to housing affordability pressures in a state already characterized by high property costs.
The insurance commissioner regulates insurers operating in California and oversees matters including rates, consumer protection, claims practices and market conduct.
The office therefore plays an important role in determining how insurers respond to rising catastrophe losses and whether homeowners can obtain affordable coverage.
Under Commissioner Ricardo Lara, California introduced the Sustainable Insurance Strategy, a series of regulatory changes intended to stabilize the market and encourage insurers to resume writing policies in higher-risk areas.
The reforms changed aspects of the state’s insurance rate-setting framework and sought to improve coverage availability.
Industry representatives have argued that the changes are beginning to support market stabilization, while acknowledging that affordability and availability remain major challenges.
The American Property Casualty Insurance Association congratulated Kim following her victory announcement but cautioned against regulatory measures that could increase insurer costs or discourage companies from offering coverage.
Kim, meanwhile, has argued that the current system requires more fundamental changes to ensure that consumers receive adequate protection.
Election results remain unofficial as counting continues
Despite Kim’s victory announcement, California’s official election process remains underway.
Millions of ballots were still outstanding when she declared victory, meaning the final margin could change as additional votes are processed.
California allows eligible vote-by-mail ballots postmarked by Election Day to arrive through November 10.
County election officials must complete their official results by December 3, with statewide certification scheduled for December 11.
Kim’s lead of approximately 404,000 votes placed her in a strong position as counting continued, but the result had not yet been formally certified.
If confirmed as the winner, she would assume responsibility for overseeing one of the country’s largest and most complex insurance markets at a time of increasing pressure from wildfire risks, higher premiums and limited coverage options.
Her immediate challenge would be translating proposals for a more publicly supported insurance system into workable policy while addressing concerns about insurer participation and the financial stability of the market.