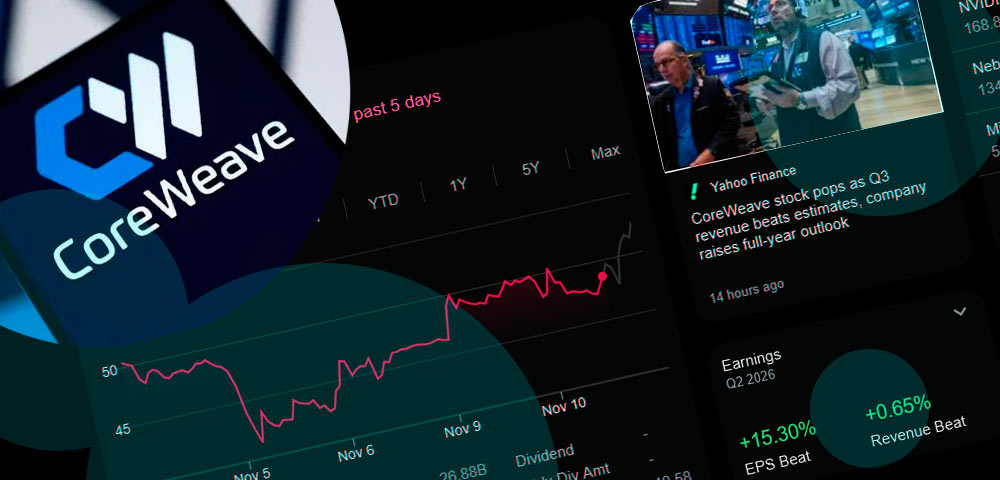
CoreWeave (NASDAQ: CRWV) shares jumped approximately 13% in premarket trading on November 11, 2026, following stronger-than-expected third-quarter results and an improved financial outlook.
The stock traded near $55, compared with its November 10 closing price of $48.73, as investors reassessed the company’s ability to finance its expanding AI infrastructure business.
- CoreWeave reported record Q3 2026 revenue of $3.66 bn, up 168%, while its backlog reached $132.5 bn. The company raised its annual revenue forecast to $13 bn–$13.3 bn, lifting CRWV shares approximately 13% in premarket trading.
- CoreWeave posted a $709 mn net loss and $846 mn in quarterly interest expenses. Management expects approximately $9 bn in customer prepayments and deposits, but projected capital expenditure of $37 bn–$39 bn keeps financing and dilution risks elevated.
- Investment bank CRWV price targets range from $39 to $140, while the broader analyst consensus stands near $125.50. Goldman Sachs, Wells Fargo and Citigroup remain bullish, although sustainable profitability is not expected until 2028.
CoreWeave reported record quarterly revenue of $3.66 bn, up 168% year over year, while its contracted revenue backlog reached $132.5 bn. Management also raised its full-year revenue guidance and outlined plans to reduce financing pressure.
The results provided relief after CRWV shares lost roughly 40% over the previous month amid concerns about debt, elevated borrowing costs and the sustainability of AI infrastructure investment.
CoreWeave Q3 2026 Earnings: Revenue Surges 168%
CoreWeave’s third-quarter revenue increased from $1.37 bn a year earlier to $3.66 bn, exceeding market expectations of approximately $3.55 bn.
Revenue backlog rose to $132.5 bn from $104.2 bn at the end of June, reflecting continued demand from AI developers, hyperscalers and enterprise customers.
The company reported GAAP operating income of $207 mn and adjusted operating income of $379 mn.
However, its net loss widened to $709 mn from $110 mn a year earlier. Net interest expense reached $846 mn, demonstrating how financing costs continue to absorb operating earnings.
CoreWeave raised its 2026 financial guidance:
| Financial metric | Updated 2026 forecast |
|---|---|
| Revenue | $13 bn–$13.3 bn |
| Adjusted operating income | $1.275 bn–$1.375 bn |
| Capital expenditure | $37 bn–$39 bn |
| Year-end annualized revenue run rate | $20 bn–$21 bn |
| Active power capacity | More than 1.85 GW |
Management expects adjusted net income to turn positive in the first half of 2028, with losses declining during 2027.
The outlook indicates improving operating performance, although substantial investment and interest payments will continue.
CoreWeave’s $132.5 bn Backlog Supports Growth but Financing Remains a Risk
CoreWeave’s backlog provides visibility into future revenue, but delivering that capacity requires additional data centers, GPUs, power infrastructure and financing. The company spent approximately $14.5 bn on capital expenditure during the third quarter alone.
Management expects approximately $9 bn in customer prepayments and deposits over the next three months. It also plans to finance infrastructure through debt facilities linked to contracted customer commitments.
CoreWeave recently secured a $2.6 bn delayed-draw financing facility, raised approximately $4.2 bn through convertible notes and established an equity issuance program covering up to 35 million shares.
These arrangements broaden its funding options but introduce refinancing and shareholder dilution risks.
Credit markets remain cautious. Ahead of the earnings release, the yield on CoreWeave’s 9.75% bonds maturing in 2031 stood near 15.5%, while five-year credit default swap spreads were approximately 1,152 basis points.
The elevated borrowing costs reflect concerns about leverage, future cash flows and the amount of financing required to fulfill existing contracts.
CoreWeave’s average debt cost was approximately 7.9% at the end of September. Maintaining access to financing near that level will be important as the company expands.
CoreWeave Stock Price Targets: Goldman Sachs, Wells Fargo and Other Investment Banks
Investment bank forecasts remain predominantly positive despite the recent decline in CRWV shares. However, several institutions have reduced their targets as financing risks increased.
| Investment bank | CRWV price target | Rating |
|---|---|---|
| Bank of America | $140 | Buy |
| Citigroup | $128 | Buy |
| Wells Fargo | $115 | Overweight |
| Goldman Sachs | $106 | Buy |
| UBS | $105 | Buy |
| Morgan Stanley | $70 | Equal Weight |
| HSBC | $39 | Sell |
Wells Fargo reduced its target from $160 to $115 while maintaining a positive rating. The bank expects strong capacity deployment and revenue growth but estimates that CoreWeave could require substantial additional borrowing to finance expansion in 2027.
Citigroup lowered its target from $159 to $128, reflecting a more cautious valuation despite continued commercial demand.
Goldman Sachs upgraded CoreWeave to Buy in October, setting a $106 target. Its positive outlook reflects the company’s position in AI computing infrastructure.
Morgan Stanley is more conservative, with a $70 target, while HSBC’s $39 forecast highlights the downside risks associated with financing costs and execution.
Across 38 analysts, the average 12-month price target stands near $125.50, implying approximately 158% upside from the November 10 closing price.
Most published targets predate the latest earnings release and may be revised.
CoreWeave Stock Forecast for 2027
CoreWeave’s share price outlook depends on three financial developments: converting backlog into revenue, controlling borrowing costs and moving toward sustainable profitability.
The bullish case assumes that demand remains strong, contracted capacity comes online as scheduled and customer prepayments reduce dependence on expensive financing.
Under these conditions, investment bank targets above $100 could become more achievable over the next 12 months.
A more cautious scenario assumes slower data center deployment, persistently high interest rates and additional share issuance. These factors could prevent operating improvements from translating into higher shareholder returns.
Wells Fargo has estimated that capital expenditure could reach approximately $66 bn in 2027 under an accelerated expansion scenario, potentially requiring at least $25 bn in additional debt.
CoreWeave has indicated that focusing on already contracted backlog could keep 2027 capital expenditure broadly in line with 2026 levels. The difference underscores how future investment decisions will affect financing requirements.
The company’s forecast of adjusted profitability in 2028 also leaves considerable execution risk over the next year.
CRWV Stock Outlook: Can the Recovery Continue?
CoreWeave’s latest earnings strengthen the argument that demand for AI computing infrastructure remains substantial.
Revenue grew nearly 170%, backlog increased by more than $28 bn sequentially, and management raised its financial outlook.
Nevertheless, the company’s valuation will depend increasingly on cash flow rather than revenue growth alone.
The immediate rebound toward $55 suggests investors are responding positively to greater financing visibility. A sustained recovery will require evidence that customer payments, borrowing facilities and operating cash generation can fund expansion without excessive dilution.
Investment bank targets remain widely dispersed, from $39 to $140 among the major institutions reviewed.
For 2027, the central question is whether CoreWeave can convert its $132.5 bn backlog into profitable revenue faster than financing costs increase.