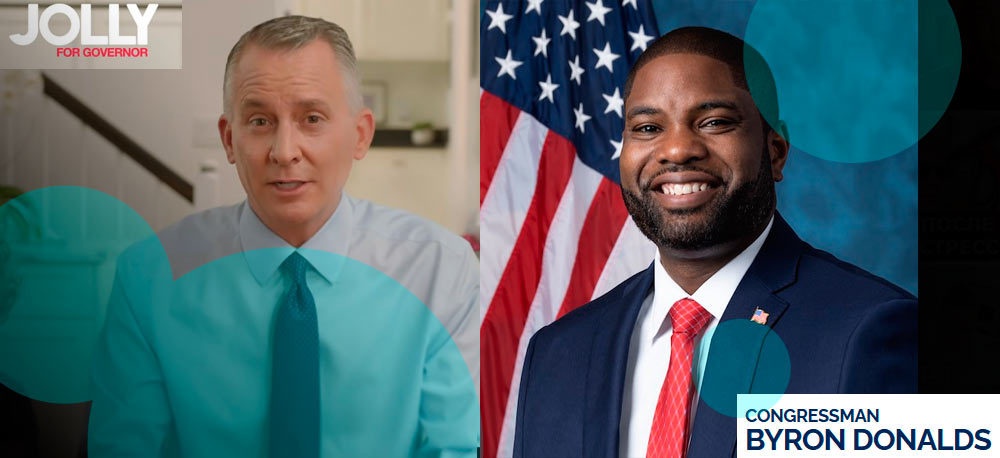
Florida gubernatorial candidates David Jolly and Byron Donalds are putting property insurance at the centre of their campaigns as the November election approaches, offering different plans for reducing homeowners’ costs.
Democratic candidate Jolly presented his latest insurance proposals on Monday, arguing that Florida’s current system gives insurers too much protection while homeowners face expensive premiums and disputes over claims.
Republican candidate Donalds is backing changes to the existing market structure rather than shifting hurricane coverage into a new state-run fund.
Jolly proposes state catastrophe fund for windstorm risk
Jolly wants Florida to create a state catastrophe fund responsible for hurricane and windstorm losses, removing those exposures from private homeowners insurance policies. He says the structure would reduce most homeowners insurance costs by more than 60%, though the estimate is a campaign projection rather than an independently established reduction.
His campaign estimates the fund would require more than $30 bn. Jolly has proposed financing it through revenue sources including taxes on insurance companies, certain real estate transactions and tourism-related revenue.
Florida already operates the Florida Hurricane Catastrophe Fund, which provides reinsurance rather than replacing primary wind coverage.
Jolly also said he would use executive action to stop property insurers from moving profits outside Florida through affiliated companies while reporting losses in the state. He cited past financial arrangements involving insurers and affiliates as part of his case for tighter controls.
The proposal follows continued complaints from homeowners about claims payments after major storms. Katie North, a West Florida resident who joined Jolly’s presentation, said her property sustained about $400,000 in damage from Hurricane Milton while her insurer paid roughly $6,000 for roof repairs.
Donalds wants changes within existing insurance market
Donalds opposes Jolly’s state catastrophe fund proposal, arguing that transferring hurricane risk to the state would ultimately expose Florida homeowners and taxpayers to losses after major storms. Jolly disputes that characterization and says his funding structure wouldn’t create the $1,000 hurricane tax alleged in Donalds campaign advertising.
Donalds instead proposes removing the 25% rapid cash buildup factor associated with premiums paid into the Florida Hurricane Catastrophe Fund.
He argues that the additional charge is no longer necessary because the fund has accumulated roughly $13 bn against a statutory limit of $17 bn, and says eliminating it would reduce insurance costs.
His insurance plan also calls for preserving Florida’s 2022 and 2023 litigation reforms, expanding or restructuring grants that help homeowners strengthen properties against storms and continuing the movement of policies from state-backed Citizens Property Insurance into the private market.
Donalds has also proposed an insurer scorecard showing pricing, claim approval and denial rates, and payment times.
Donalds has said his broader insurance program would reduce premiums by about 20% to 30%. Like Jolly’s projected savings, the figure represents the candidate’s estimate of the effect of his proposed policies rather than a guaranteed premium reduction.
The two candidates are therefore approaching Florida’s property insurance problem from different directions. Jolly proposes moving hurricane and wind exposure away from private insurers and into a larger state-backed structure, while Donalds would retain the private-market model and change its catastrophe charges, mitigation programs and regulation.