- Rocket Lab Q3 2026 Earnings: Revenue Growth Accelerates
- Rocket Lab’s $3.6 bn Backlog Strengthens Revenue Visibility
- Neutron Launch Delay Remains the Main Risk for RKLB Stock
- Rocket Lab Stock Price Targets: Investment Banks Maintain Bullish Forecasts
- RKLB Stock Forecast for 2027: What Will Determine the Next Move?
Rocket Lab (NASDAQ: RKLB) reported record third-quarter 2026 revenue of $267.8 mn, up 73% year over year, while its order backlog climbed 52% sequentially to $3.57 bn. The company also generated positive GAAP operating cash flow of $7.2 mn, marking progress toward financial sustainability.
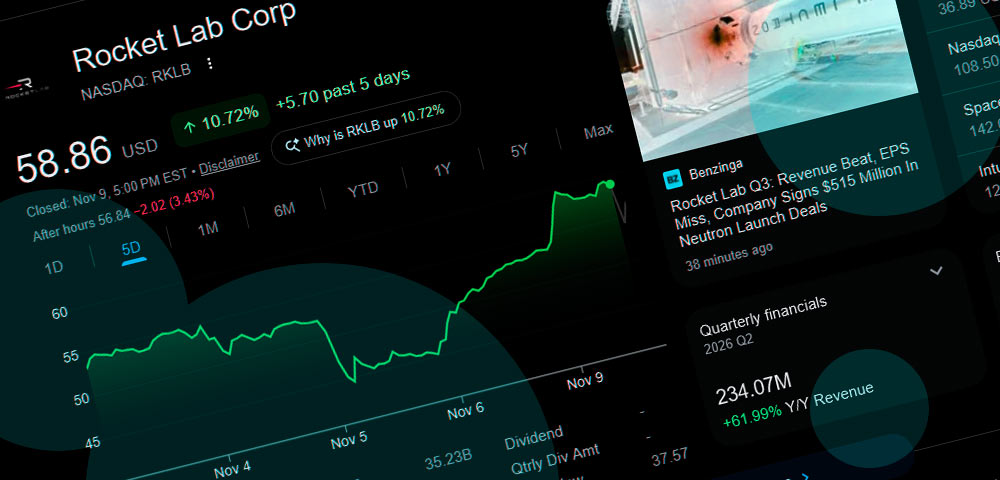
RKLB shares closed November 9 at $58.86, gaining 10.9% during regular trading, before initially declining approximately 4.5% in after-hours trading following the earnings release.
- Rocket Lab reported record Q3 2026 revenue of $267.8 mn, up 73% year over year, while its backlog surged 52% to $3.57 bn. The company generated $7.2 mn in positive operating cash flow but posted a $79.7 mn net loss.
- Rocket Lab secured approximately $1 bn in new launch contracts, including over $515 mn for Neutron. Its launch backlog reached 117 missions, but Neutron’s debut has been pushed to 2027, creating execution and revenue timing risks.
- Wall Street’s average 12-month RKLB stock price target stands at $102.15, implying approximately 74% upside from the November 9 close of $58.86. Investment bank forecasts range from $67 to $132, reflecting uncertainty over profitability, Neutron development and the Iridium acquisition.
The reaction reflected continued concerns about profitability, the Neutron rocket’s launch schedule and the company’s valuation.
Rocket Lab Q3 2026 Earnings: Revenue Growth Accelerates
Revenue exceeded the company’s previous guidance of $250 mn to $265 mn and increased by approximately $34 mn from the second quarter.
However, Rocket Lab’s GAAP net loss widened to $79.7 mn from $18.3 mn a year earlier. Despite positive operating cash flow, the company remains unprofitable.
For the fourth quarter, management forecasts:
- Revenue of $270 mn to $290 mn.
- GAAP gross margin of 34% to 36%.
- Non-GAAP gross margin of 39% to 41%.
- Adjusted EBITDA loss of $14 mn to $20 mn.
Based on reported results and Q4 guidance, Rocket Lab is positioned to generate approximately $972 mn to $992 mn in revenue for 2026, compared with $601.8 mn in 2025.
The projected increase demonstrates strong commercial demand, although revenue expansion has yet to translate into consistent earnings.
Rocket Lab’s $3.6 bn Backlog Strengthens Revenue Visibility
Rocket Lab secured approximately $1 bn in new launch contracts during the third quarter, lifting its total launch backlog to a record 117 missions.
More than $515 mn came from Neutron launch agreements, increasing the medium-lift rocket’s contracted backlog to 16 missions. Several contracts carry a base launch price of $70 mn.
The company also signed approximately $470 mn in Space Systems contracts and has more than 55 spacecraft under development. These commitments support revenue visibility beyond 2026 and reduce Rocket Lab’s dependence on its Electron launch business.
However, backlog represents contracted future business rather than recognized revenue. Its conversion into sales depends on manufacturing capacity, mission schedules and successful launches.
Neutron Launch Delay Remains the Main Risk for RKLB Stock
Rocket Lab now targets Neutron’s first flight no earlier than 2027. The reusable medium-lift rocket is central to the company’s long-term strategy because it expands Rocket Lab’s addressable launch market and enables larger satellite deployment contracts.
Neutron has already attracted significant commercial demand before its debut. Nevertheless, the development schedule introduces uncertainty around the timing of revenue recognition and the profitability of future missions.
Further delays could increase development spending and postpone expected cash flows. Successful testing and an initial launch would remove a major source of uncertainty from the stock’s valuation.
The pending acquisition of Iridium Communications introduces another factor. Rocket Lab has completed an equity offering to fund the transaction and reported cash and cash equivalents of $4.45 bn at September 30.
The acquisition could expand recurring revenue opportunities, but the associated share issuance creates dilution, while integration adds execution risk.
Rocket Lab Stock Price Targets: Investment Banks Maintain Bullish Forecasts
Wall Street’s outlook remains predominantly positive despite the sharp correction in RKLB shares during 2026.
The average 12-month analyst price target stood at approximately $102.15, based on 22 analysts, implying around 74% upside from the November 9 regular-session closing price.
Recent investment bank forecasts include:
| Investment bank | RKLB price target | Rating |
|---|---|---|
| Morgan Stanley | $105 | Buy |
| Cantor Fitzgerald | $122 | Buy |
| Stifel | $132 | Buy |
| Bank of America | $110 | Buy |
| Goldman Sachs | $67 | Neutral |
| Citizens JMP | $90 | Buy |
These targets were issued before the November 9 earnings announcement and may change following the latest results.
Bullish forecasts reflect Rocket Lab’s expanding backlog, growing government and commercial contracts, and opportunities in satellite manufacturing and medium-lift launches.
More cautious assessments focus on the company’s continuing losses, execution requirements for Neutron and the risk that anticipated future growth is already reflected in its valuation.
The difference between the $67 and $132 targets illustrates how heavily Rocket Lab’s valuation depends on assumptions about its 2027–2028 operating performance.
RKLB Stock Forecast for 2027: What Will Determine the Next Move?
Rocket Lab enters 2027 with stronger contracted demand and a substantially larger business than a year earlier. Its near-term stock performance, however, will depend on whether revenue growth improves operating margins and reduces losses.
Three developments are particularly important:
- Neutron’s first launch. Successful execution would strengthen confidence in the company’s ability to fulfill its growing medium-lift backlog.
- Revenue conversion and profitability. Investors will monitor whether the $3.57 bn backlog produces sustained sales growth, higher margins and positive free cash flow.
- Iridium acquisition. Completion and integration will determine whether the transaction strengthens Rocket Lab’s financial profile sufficiently to offset dilution.
The latest results improve the fundamental outlook, but they do not eliminate valuation risk. Rocket Lab’s share price has already demonstrated substantial sensitivity to changes in expectations for space infrastructure spending and launch schedules.
The existing analyst consensus points to significant potential appreciation over the next 12 months. Achieving those targets will require Rocket Lab to deliver on its record order book while demonstrating that its expanding operations can support a more profitable business.