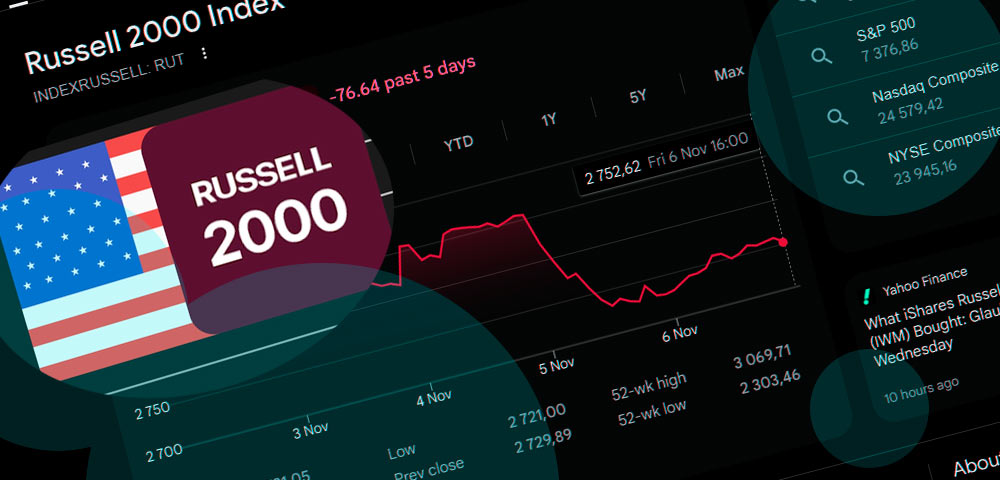
The Russell 2000 recovered on November 6, 2026, following Thursday’s 4.45% selloff, as stronger US employment data supported expectations of continued economic growth. However, higher Treasury yields and the prospect of further Federal Reserve rate increases remain significant risks for smaller companies.
The Russell 2000 closed near 2,756.24, gaining approximately 0.97% on Friday. The index had fallen 127.06 points to 2,729.89 on November 5 as selling spread across US equities.
- The Russell 2000 rebounded 0.97% to 2,756.24 on November 6 after plunging 4.45% the previous day. Small-cap stocks remained under pressure from elevated borrowing costs and uncertainty over Federal Reserve policy.
- US employers added 165,000 jobs in October, exceeding forecasts, while unemployment fell to 4.1%. Stronger economic growth supports domestic businesses, but the increased probability of a December Fed rate hike poses risks for highly leveraged small-cap companies.
- J.P. Morgan expects improving small-cap earnings in 2027, while Neuberger Berman warns that approximately 45% of small-cap debt carries floating interest rates. Standard Chartered sees signs of market stabilization but expects further monetary tightening through the first half of 2027.
Despite the recovery, small-cap stocks remained lower for the week. Investors are reassessing whether improving domestic demand can offset rising financing costs and weaker risk appetite.
US employment growth supports small-cap earnings outlook
The US economy added 165,000 jobs in October, exceeding expectations of approximately 65,000. The unemployment rate declined to 4.1%, while average hourly earnings increased 0.4% during the month and 3.1% year over year. The report strengthened expectations that consumer spending and business activity will remain resilient.
Smaller US companies are generally more dependent on domestic revenue than multinational corporations. Consequently, sustained employment growth can support earnings across regional banks, healthcare providers, industrial companies and consumer businesses.
Manufacturing data also indicated continued expansion. September factory orders increased 1.8%, while October’s Logistics Managers’ Index reached 70.7.
The problem for Russell 2000 companies is that stronger economic activity may delay monetary easing.
Following the employment report, futures markets increased the implied probability of a December Federal Reserve rate hike to approximately 78%.
The 10-year Treasury yield approached 4.85%, adding pressure to smaller companies with substantial borrowing requirements.
Investment banks remain divided on Russell 2000 outlook
J.P. Morgan Asset Management maintains a constructive longer-term view of US small-cap equities, citing improving earnings expectations, relatively attractive valuations and increasing industrial investment.
The bank expects small-cap earnings growth to strengthen in 2027 as economic activity broadens beyond the largest technology companies.
However, its research identifies financial leverage as a major vulnerability.
Approximately 41.5% of small-cap corporate debt carries floating interest rates, compared with 18% among large-cap companies. Smaller companies also have substantially weaker interest coverage. This makes Russell 2000 earnings particularly sensitive to changes in Federal Reserve policy.
Neuberger Berman’s fourth-quarter outlook is more cautious. Its research indicates that approximately 45% of small-cap debt is floating-rate, while more than 28% of Russell 2000 companies have negative forward earnings estimates.
The firm also notes that aggregate 2026 earnings forecasts for the index have declined by more than 5% since July. Standard Chartered’s November 6 assessment identifies increasing signs of stabilization across US equities following the recent volatility spike.
However, the bank still expects two additional Federal Reserve rate increases by the first half of 2027, suggesting that financing conditions could remain restrictive.
Russell 2000 valuations and earnings risks
The Russell 2000 trades at a substantial valuation discount to major US large-cap benchmarks, although comparisons are complicated by the index’s relatively high proportion of unprofitable companies.
Smaller businesses have less access to inexpensive long-term financing and generally maintain lower cash reserves than major corporations.
Higher interest rates can therefore affect their operating margins more quickly. At the same time, the Russell 2000 has significantly less exposure to mega-cap technology stocks than the S&P 500. Its greater concentration in healthcare, financial services and industrial businesses provides a different earnings profile. This distinction became important during the latest AI-driven selloff.
Although smaller companies were not the main source of concerns about data-center investment, the Russell 2000 still fell 4.45% on Thursday as investors reduced exposure to riskier equities.
iShares Russell 2000 ETF reflects changing investor sentiment
The iShares Russell 2000 ETF (IWM), one of the main instruments tracking US small-cap equities, also recovered on Friday. IWM closed near $272.53, compared with $270.98.
Recent trading activity has highlighted interest in healthcare and financial companies, including Glaukos, Jackson Financial, Essent Group and Radian Group.
However, changes in ETF holdings do not necessarily indicate active investment decisions. Index-tracking funds routinely adjust positions in response to investor flows and index composition.
The more important indicators for small-cap performance remain earnings revisions, borrowing costs and the availability of credit.
Russell 2000 forecast for November 2026
The index’s recovery toward 2,756 suggests that selling pressure moderated following Thursday’s sharp decline.
The 2,720-2,730 area represents an immediate technical reference after the November 5 selloff. A sustained move above 2,800 would indicate improving momentum, while the previous 2,850-2,860 trading area presents a more substantial potential resistance zone.
Investment-bank forecasts support a cautiously constructive medium-term outlook, particularly if corporate earnings improve and domestic economic growth remains resilient.
However, small-cap stocks face a difficult combination of elevated borrowing costs, uncertain Federal Reserve policy and uneven profitability.
The next direction of the Russell 2000 will depend on whether improving earnings expectations can compensate for higher interest expenses.
For November, employment growth and domestic demand remain supportive, but the prospect of additional interest-rate increases limits the strength of the recovery.