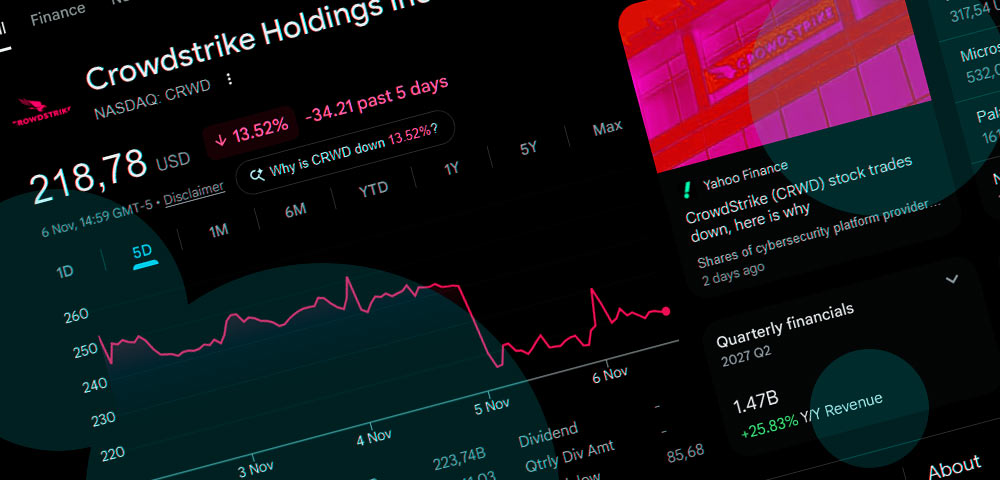
CrowdStrike shares recovered modestly on November 6, 2026, following a sharp decline across cybersecurity and artificial intelligence stocks. Investment banks remain largely bullish on CRWD, citing accelerating subscription revenue and growing demand for AI security, although elevated valuations continue to concern investors.
CrowdStrike traded at $218.73, up 0.7%. The recovery followed Thursday’s 9.9% decline, when institutional investors reduced exposure to some of the year’s strongest-performing software stocks.
- CrowdStrike shares rebounded 0.7% to $218.73 on November 6 after plunging 9.9% on Thursday. Despite the selloff, CRWD remains approximately 61% higher over the past year, outperforming the broader US stock market.
- CrowdStrike’s annual recurring revenue increased 25% to $5.84 bn, while net new ARR surged 51% to a record $333 mn. The company also announced $495 mn in AI security acquisitions and introduced an AI Kill Switch to expand its cybersecurity platform.
- Investment banks remain bullish on CRWD. UBS targets $310, Deutsche Bank and Wells Fargo $300, Citigroup $295, and Morgan Stanley $254. The average analyst price target of $248.45 implies approximately 14% upside from November 6 levels.
Despite the correction, CrowdStrike shares remain approximately 61% higher over the past 12 months, substantially outperforming the broader US stock market.
CrowdStrike stock price targets: Deutsche Bank, UBS and Morgan Stanley
Wall Street’s latest forecasts suggest considerable upside potential, although investment banks differ on valuation.
Deutsche Bank upgraded CrowdStrike from Hold to Buy on November 2 and raised its 12-month price target from $240 to $300.
The bank expects artificial intelligence to accelerate cybersecurity spending as companies deploy autonomous software agents and expand their digital infrastructure.
Deutsche Bank also believes CrowdStrike could achieve its $10 bn annual recurring revenue target ahead of fiscal 2030.
Other investment-bank forecasts include:
- UBS: $310 price target.
- Wells Fargo: $300.
- Citigroup: $295.
- Bank of America: $290, with a Hold rating.
- Mizuho: $275.
- Morgan Stanley: $254.
- Jefferies: $240.
The average 12-month analyst price target stands near $248.45, implying approximately 14% upside from the November 6 trading price.
The difference between the average forecast and the most bullish targets reflects uncertainty over how much future cybersecurity growth is already reflected in CRWD’s valuation.
CrowdStrike subscription revenue growth accelerates
CrowdStrike’s latest quarterly results showed improving demand for its Falcon cybersecurity platform.
In the second quarter of fiscal 2027, ended July 31, 2026, revenue increased 26% year over year to $1.47 bn, while subscription revenue rose 27% to $1.40 bn.
Annual recurring revenue reached $5.84 bn, up 25%, with net new ARR climbing 51% to a record $333 mn.
Falcon Flex, the company’s flexible subscription offering, continued expanding. ARR from customers using the program reached $2.29 bn, representing 101% annual growth.
Free cash flow increased to $377 mn, compared with $284 mn a year earlier. Management expects fiscal 2027 revenue of approximately $5.99-6.01 bn and ending ARR of $6.60-6.61 bn.
For the third quarter, which ended October 31, CrowdStrike previously projected revenue of $1.523-1.529 bn. The upcoming earnings report will show whether subscription momentum continued during the latest period.
CrowdStrike expands AI security business through acquisitions
CrowdStrike announced agreements on November 3 to acquire Fiddler AI and Dreadnode for a combined consideration of approximately $495 mn.
Fiddler specializes in monitoring AI agents and explaining their decisions. Its technology will support Falcon Observe, extending CrowdStrike’s capabilities beyond traditional endpoint security.
Dreadnode develops automated security testing tools designed to identify weaknesses in AI models, applications and autonomous agents before deployment.
The acquisitions are expected to strengthen CrowdStrike’s position in a cybersecurity market increasingly shaped by AI-driven applications.
The company also introduced an AI Kill Switch within Falcon Guardian, allowing security teams to stop unauthorized or malfunctioning AI agents.
These developments expand CrowdStrike’s addressable market but also introduce integration costs and additional competition from established cloud providers and emerging AI security companies.
Why did CrowdStrike shares fall nearly 10%?
Thursday’s decline reflected a broader repricing of highly valued technology companies rather than a deterioration in CrowdStrike’s latest operating results.
Cybersecurity stocks had significantly outperformed traditional software companies throughout 2026. Investors consequently had substantial unrealized gains to protect when volatility increased.
CrowdStrike fell alongside Okta, Palo Alto Networks, Rubrik and Cloudflare, while previously weakened software companies experienced smaller declines.
The selloff also followed concerns about tighter AI regulation after the US midterm elections and uncertainty surrounding future technology infrastructure spending.
CrowdStrike’s financial exposure differs from that of semiconductor manufacturers and data-center operators.
Its principal revenue comes from recurring cybersecurity subscriptions rather than spending on AI computing infrastructure. AI adoption could increase demand for its products even if construction of new data centers slows.
The greater risk is that the development of autonomous security tools changes competitive dynamics, potentially reducing demand for some existing cybersecurity services.
CrowdStrike stock forecast for November 2026
The near-term outlook remains sensitive to technology-sector volatility and expectations for Federal Reserve interest rates.
CRWD’s November 6 trading range of approximately $217-231 provides immediate reference points for short-term price movements. A sustained recovery above $230 would indicate improving momentum following Thursday’s decline.
The company’s next earnings report will be more important for its medium-term valuation.
Investors will focus on net new ARR growth, Falcon Flex adoption, free cash flow and the profitability of newer cloud, identity and AI security products.
Investment banks generally expect cybersecurity demand to remain strong as enterprises expand their use of artificial intelligence. Nevertheless, CrowdStrike’s premium valuation leaves limited room for disappointing results.
The fundamental outlook remains supported by recurring revenue growth and expanding AI security capabilities. Whether CRWD approaches the higher Wall Street price targets will depend on sustained subscription acceleration and stronger earnings conversion, rather than a recovery in technology-sector sentiment alone.