Follow Beinsure
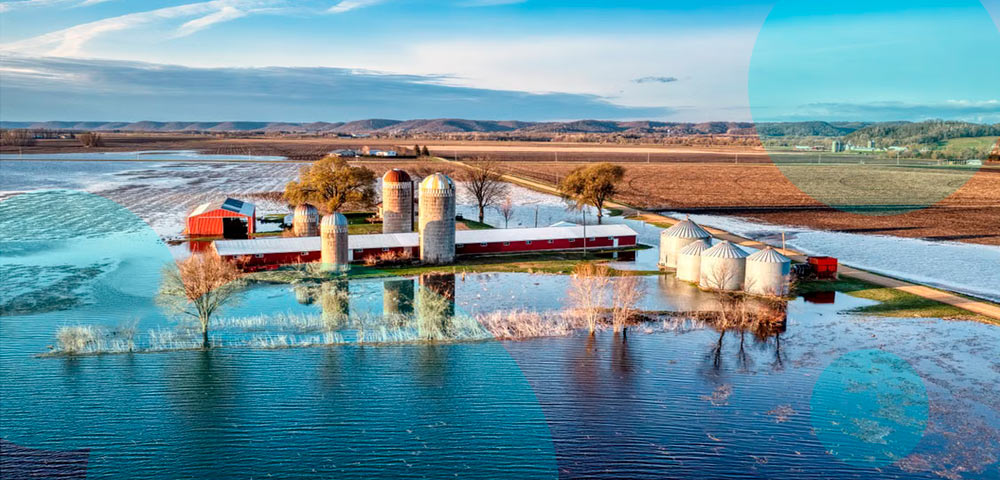
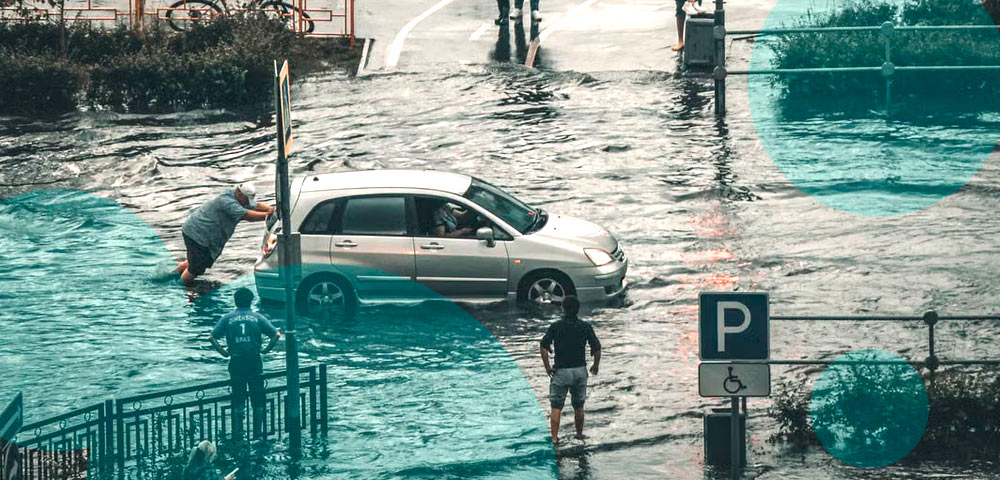
Flooding across the US, including severe events in Kentucky and thunderstorms in the Plains and Midwest, has exposed substantial gaps in property insurance coverage. Floods generated billions of dollars in insured losses during 2025, yet fewer than 4% of US homes have flood insurance, according to FEMA.
Moody’s analysis found that insured US flood losses totaled $319 bn between 2000 and 2024, compared with more than $1.58 tn in uninsured losses. The firm estimates that uninsured flood losses could rise by another 25% by 2050.
- Fewer than 4% of US homes have flood insurance, while uninsured flood losses reached more than $1.58 tn between 2000 and 2024, according to FEMA and Moody’s.
- Flood insurance endorsements typically cost $40-$50 annually, compared with hundreds or thousands of dollars for some standalone policies.
- Munich Re US offers a Personal Lines Inland Flood Coverage Endorsement that allows insurers to provide additional protection through existing property policies.
The coverage gap extends well beyond properties in designated high-risk flood zones. About 40% of National Flood Insurance Program (NFIP) flood claims originate outside special flood hazard areas (SFHAs), leaving many homeowners exposed to losses they may not have anticipated.
For property owners seeking additional protection, flood insurance endorsements attached to existing property policies may offer a less expensive alternative to standalone flood coverage.
Flood insurance endorsements provide an alternative to standalone policies
Seth Piechowski, Senior Market Development Manager at Munich Re US, told that inland flood endorsements can provide meaningful financial protection without requiring homeowners to purchase a separate flood insurance policy.
40% of NFIP flood insurance claims come from outside special flood hazard areas. So it’s really important that those folks have proper coverage too.
Standalone flood policies can be expensive, particularly when coverage limits approach a building’s total insured value. Yet many flood incidents result in partial damage rather than the complete destruction of a property.
According to Piechowski, annual premiums for flood endorsements typically range from $40 to $50, while standalone policies can cost hundreds or even thousands of dollars.
For most flood events, you are not going to see a total loss, and as a result, flood endorsements provide supplemental coverage that typically is close to, if not at, replacement cost for a lot of these claims that occur.
Endorsements can also provide coverage benefits that, in some circumstances, exceed those available through separate flood policies.
Lower premiums and simpler insurance administration
Adding an inland flood endorsement to an existing homeowners policy allows policyholders to obtain supplemental protection through their current insurance agent and carrier.
The arrangement eliminates the need to compare and manage additional standalone policies, reducing administrative work for both insurance agents and customers.
“From an agent standpoint, you’re eliminating an additional policy that has to be bound and maintained, as well as having to re-enter any policyholder information. And from a policyholder standpoint, the cost piece is a big benefit,” Piechowski said.
Rather than purchasing flood insurance from a separate provider, homeowners can request additional protection through their existing property insurance arrangements.
This approach combines the base property premium and optional flood coverage under a single policy, with the endorsement generally carrying a substantially lower additional cost than a standalone alternative.
The financial advantage is particularly relevant to homeowners outside designated flood hazard areas who may face flood exposure but have not purchased separate protection.
Single-carrier claims handling can reduce complexity
Beyond lower premiums, flood endorsements can simplify claims administration when a property experiences multiple types of damage during the same event.
A homeowner with separate property and flood insurance policies may need to deal with different insurers, claims adjusters and coverage assessments. An endorsement can allow the claims process to remain with one carrier.
“On the off-chance that a loss does occur, you create an environment where you’re only working with one carrier,” Piechowski told. “With that carrier, not only are you able to file one claim and work with them on the flood component, you are also able to work with them for any other type of peril that may have caused additional damage or created an exposure issue.”
Piechowski said this arrangement can be particularly useful in claims involving basement damage and water backup, where determining which policy provisions apply may otherwise require coordination between multiple parties.
With an endorsement, policyholders are more likely to work with a single claims adjuster, reducing the exchanges that can arise between separate flood adjusters and property claims inspectors.
The approach can make it easier to establish how different components of a loss are assessed and handled within the existing insurance relationship.
Inland flood coverage reduces homeowners’ financial exposure
For homeowners concerned about unexpected property losses, optional flood endorsements offer an alternative to retaining the full financial risk themselves.
Customers who are particularly concerned about risk have historically been more inclined to purchase affordable optional insurance protection.
By adding an endorsement instead of self-insuring, your insureds have a $50 to $100 premium to cover tens of thousands of dollars should a flood event occur compared to paying it out on their own – and taking a significant hit to their wallet.
The value proposition has two components: a relatively modest additional premium compared with purchasing standalone coverage, and financial protection against potentially substantial flood damage.
For insurers, incorporating flood protection into an existing property policy also reduces the administrative requirements associated with issuing and maintaining separate contracts.