Overview
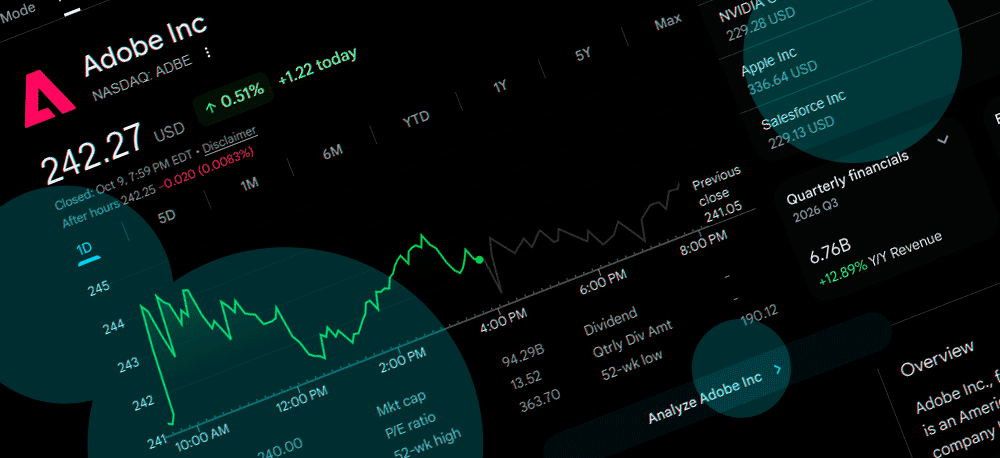
Adobe Inc. (NASDAQ: ADBE) shares ended the latest trading week with two consecutive gains, recovering some ground after months of declining valuations and investor concerns about artificial intelligence competition. The stock closed at $242.27 on October 9, up 0.51% for the session.
The recovery followed an extended period of underperformance. Adobe shares have lost approximately 31% over the past 12 months, compared with a 17% gain for the S&P 500.
Year-to-date losses are also substantial, despite the company’s continued revenue growth and expanding AI product portfolio.
- Adobe (ADBE) shares closed at $242.27 on October 9, 2026, gaining 0.51% after a 3.56% rebound the previous session. The stock remains approximately 31% lower over 12 months, with technical indicators pointing to continued weakness.
- Adobe expanded its AI partnerships with Heathrow Airport and the NHL, strengthening its enterprise customer experience business. The company also faces uncertainty after its suspension from the U.S. Permanent Labor Certification Program.
- Analysts maintain a mixed outlook, with a consensus Hold rating and an average price target around $265–$269. Adobe’s latest annual revenue guidance of $26.576–$26.626 bn and growing AI subscriptions support its fundamentals, although slower recurring revenue growth remains a concern.
The latest developments present conflicting signals for investors. Adobe has secured new enterprise AI partnerships with Heathrow Airport and the National Hockey League, supporting its strategy of integrating AI into digital marketing and customer experience software.
At the same time, the company’s suspension from a U.S. employment-based immigration certification program introduces a new regulatory risk.
Adobe’s financial performance remains profitable, with fiscal third-quarter revenue increasing 13% to $6.76 bn. Yet slower growth in contracted business and the potential impact of AI competitors on its established subscription products continue to weigh on expectations.
As of October 11, 2026, investors are assessing whether the recent share-price recovery represents the beginning of a sustained rebound or another temporary advance within a longer-term downtrend.
Adobe expands AI partnership with Heathrow Airport
On October 8, Adobe announced an expanded partnership with Heathrow Airport to improve digital services for more than 84.5 mn annual passengers through artificial intelligence and personalized customer experiences.
The agreement builds on a relationship spanning more than a decade and will introduce Adobe CX Enterprise, an AI-powered platform designed to manage customer interactions and digital engagement.
Heathrow plans to use Adobe technology to develop a new flagship website serving more than 50 mn visitors annually. The platform will provide personalized travel information, accessibility resources and content for passengers, local communities and government stakeholders.
The airport will also deploy Adobe Experience Manager and Adobe Brand Visibility to improve how its information appears across AI-powered platforms, including ChatGPT, Google Gemini, Microsoft Copilot and Perplexity AI.
Adobe Brand Visibility will help Heathrow monitor how AI systems reference its content, identify gaps in search visibility and improve the accuracy of information available to travelers.
According to Adobe research, one in four consumers now uses AI platforms as their primary information source when making travel decisions.
The Heathrow agreement follows Adobe’s September 28 partnership with the National Hockey League. As an official creative, marketing and AI partner, Adobe will provide technology supporting personalized digital engagement across the NHL and its 32 clubs.
The partnership includes Adobe GenStudio, Adobe Experience Platform and Adobe Journey Optimizer, enabling the league to create content and tailor customer interactions across digital channels.
Neither partnership announcement disclosed financial terms sufficient to determine its immediate contribution to Adobe’s revenue.
U.S. immigration restrictions introduce a new risk
Adobe faces additional uncertainty after the U.S. government announced on October 8 that the company would be suspended from the Permanent Labor Certification Program, commonly known as PERM.
The program enables employers to sponsor foreign workers seeking employment-based permanent residency. The government said it would stop accepting new applications and processing pending applications involving the affected companies.
The measures also apply to Microsoft and several major technology services providers, including Infosys, Cognizant, Tata Consultancy Services, Wipro, HCL Technologies and Capgemini.
The suspension does not automatically terminate existing H-1B employment visas, but it creates uncertainty for employees pursuing permanent residency and employers seeking to retain specialized international talent.
For Adobe, the potential implications concern recruitment and employee retention in technical fields supporting AI development, enterprise software and cloud services.
The duration of the restrictions remains uncertain. Adobe has not disclosed a quantified financial impact, making it premature to estimate how the decision might affect operating expenses or future revenue growth.
Adobe stock price forecast and analyst ratings
Wall Street analysts remain divided over Adobe’s recovery prospects, reflecting the contrast between its profitability and uncertainty surrounding future AI competition.
The stock carries a consensus Hold rating. Published analyst price-target averages range from approximately $265.09 to $268.82, depending on the analysts included in the calculation.
Against Adobe’s October 9 closing price of $242.27, those estimates imply approximately 9.4% to 11% potential upside over the usual 12-month target horizon.
Recent analyst actions illustrate the differences in expectations.
- DA Davidson maintained its Buy recommendation on September 14 and increased its target from $250 to $290.
- Piper Sandler maintained a Neutral rating on September 11, raising its target from $240 to $250.
- Citigroup also maintained a Neutral recommendation but reduced its target from $301 to $250.
- Other September revisions included JPMorgan’s $315 target, Wells Fargo’s $270 forecast and Jefferies’ $275 estimate.
The distribution indicates that analysts see possible upside from current levels, but the extent of any recovery depends on Adobe’s ability to maintain subscription growth and demonstrate further AI monetization.
Adobe trades at approximately 13 times trailing earnings, compared with about 21.5 times for the S&P 500.
That discount reflects market concerns about growth rather than an absence of profitability.
A separate investor valuation narrative estimates Adobe’s fair value at $319.96, suggesting approximately 24% undervaluation relative to the estimated fair value. Reaching that valuation from $242.27 would require a share-price increase of roughly 32%.
This is an investor valuation scenario, not an analyst consensus forecast. It depends on assumptions about Adobe’s earnings growth, cash generation and ability to defend its pricing power against AI competitors.
Adobe earnings outlook: revenue and AI subscriptions
Adobe’s financial results provide a stronger picture than its recent share-price performance. For the fiscal third quarter ended August 28, 2026, revenue increased 13% year over year to a record $6.76 bn. GAAP diluted earnings reached $4.62 per share, while non-GAAP diluted earnings were $6.13.
The company reported GAAP operating income of $2.35 bn and non-GAAP operating income of $2.97 bn. Cash generated from operations reached $2.52 bn.
Total annualized recurring revenue stood at $27.50 bn at quarter-end, while subscription revenue increased 14% to $6.56 bn.
Adobe’s AI-first annualized recurring revenue grew more than 150% year over year, demonstrating increasing adoption of AI-related products. The company also reported more than 1 bn monthly active users across its creativity and productivity offerings.
Sales under contract increased 8% in fiscal Q3, compared with 13% reported revenue growth. Management attributed part of the difference to a strategy focused on attracting users through free products before converting them into paid subscriptions.
Adobe’s free creative applications have surpassed 100 mn users, an increase of more than 70% year over year. The commercial challenge is converting that expanded audience into recurring revenue without weakening subscription pricing.
- For fiscal Q4 2026, management expects revenue of $6.80 bn to $6.85 bn, compared with $6.76 bn in the preceding quarter.
- GAAP earnings per share are forecast between $4.65 and $4.70, while non-GAAP earnings are expected to reach $6.30 to $6.35.
- Adobe also raised its full-year revenue forecast to $26.576 bn–$26.626 bn and projected non-GAAP earnings per share of $24.45–$24.50.
- Management expects ending annualized recurring revenue growth of 10.2% for the fiscal year, below the 11.2% rate reported at the end of Q3.
Whether Adobe meets that target will be an important indicator of subscription retention, customer conversion and the commercial performance of its AI investments.
Adobe valuation, cash flow and ETF exposure
Adobe’s substantial cash generation remains a central argument supporting its valuation.
The company generated approximately $10.6 bn in free cash flow over the latest 12-month period and repurchased around $9.3 bn of shares.
Its share count has declined approximately 13.4% over three years, supporting earnings per share by distributing profits across fewer outstanding shares.
Approximately $24.55 bn remained available under its share repurchase authorization. The difference suggests that the company’s established profitability and financial position have not been sufficient to reverse weaker share-price momentum or concerns about future expansion.
Changes in fund allocations and investor flows can influence demand for Adobe shares, although these positions do not independently establish a directional price forecast.
Adobe stock forecast for the remainder of 2026
Adobe enters the next trading week with improving short-term price performance but unresolved questions about subscription growth, AI competition and the impact of U.S. immigration restrictions.
The immediate technical outlook depends on whether the stock can establish support above $243–$249 and eventually recover toward the $258 area. Failure to sustain the rebound would leave the $224.50 support level in focus.
Analyst targets around $265–$269 imply modest recovery potential compared with more optimistic valuation scenarios approaching $320.
The company’s next earnings report will provide more substantial evidence than short-term price movements.
Investors will be watching whether fourth-quarter revenue reaches the projected $6.80 bn–$6.85 bn range, whether annualized recurring revenue growth meets management’s 10.2% full-year target and whether AI-first subscription products can offset softer growth in contracted business.
Adobe’s expanded relationships with Heathrow and the NHL provide additional enterprise applications for its AI software, but their financial contribution has not been disclosed.
The stock’s valuation already reflects considerable skepticism about Adobe’s future growth. Its recovery prospects now depend on whether the company can convert its expanding AI user base and enterprise partnerships into sustained subscription revenue and earnings growth.