Overview
- Meta stock price forecast for 2027: What would $1,000 require?
- Meta advertising revenue rises 27% as AI improves performance
- Meta Muse AI could become a new revenue source
- Meta’s Muse faces privacy and profitability concerns
- Meta AI spending could reach $145 bn in 2026
- Meta develops Iris AI chip to reduce infrastructure costs
- Reality Labs losses remain a financial burden
- Regulatory pressure threatens Meta’s earnings
- Meta Q3 2026 earnings forecast and October outlook
Meta Platforms (NASDAQ: META) enters the final quarter of 2026 with its advertising business delivering strong revenue growth, a newly launched AI assistant attracting millions of users and a capital investment program that is putting increasing pressure on cash flow.
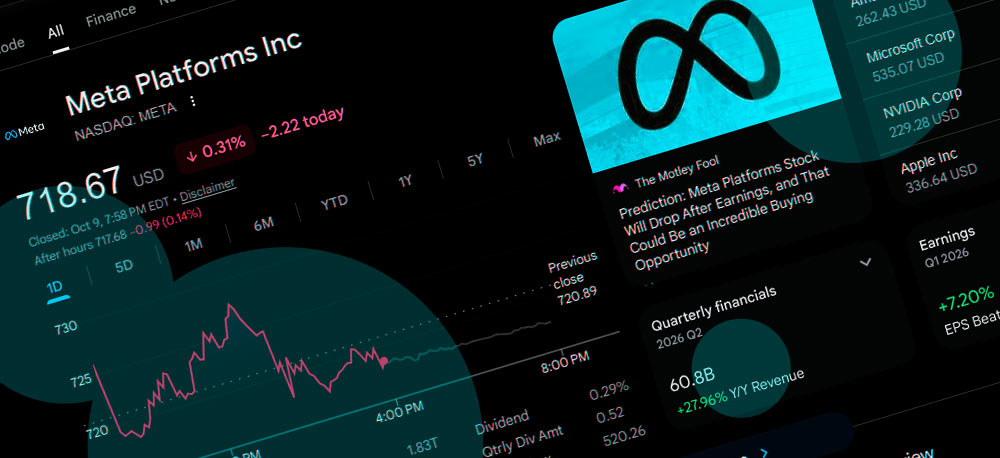
Meta shares last closed at $718.67 on October 9, declining 0.31% during the session. The stock had fallen 0.06% on October 8 after a 2.38% decline the preceding day, extending a pullback following September’s 26.79% rally, its strongest monthly performance since 2022. That September advance had lifted year-to-date gains to 10.13%.
- Meta Platforms shares closed at $718.67 on October 9, 2026. A move to $1,000 would represent 39.1% upside, while the average analyst target of $793.91 implies a more moderate 10.5% gain.
- Meta’s Q2 revenue grew 28% to $60.80 bn, supported by 27% advertising growth. Its Muse AI assistant could generate more than $27 bn in annual revenue by 2030, according to Citigroup’s forecast.
- Meta expects $130–$145 bn in 2026 capital expenditures, putting pressure on free cash flow. Its next earnings report will test whether advertising growth can offset AI infrastructure costs, Reality Labs losses and legal expenses.
The company has a market capitalization of approximately $1.84 trillion, with investors weighing the earnings potential of its artificial intelligence investments against rising infrastructure expenses and regulatory liabilities.
Wall Street remains broadly positive. Wells Fargo raised its Meta price target to $1,000 on October 6, while Citigroup expects the company’s new Muse AI assistant could generate more than $27 bn in annual revenue by 2030.
Neither forecast removes the immediate financial challenge. Meta is spending heavily to build AI infrastructure, and its second-quarter free cash flow declined sharply despite continued growth in advertising revenue.
Meta stock price forecast for 2027: What would $1,000 require?
Analyst forecasts indicate considerable room for Meta’s share price to appreciate, although expectations differ substantially.
An analyst survey published in early October placed the average price target at $793.91, with eight Strong Buy ratings, 47 Buy ratings, seven Holds and no Sell recommendations.
Relative to Meta’s October 9 closing price of $718.67, that target implies approximately 10.5% upside. Wells Fargo analyst Ken Gawrelski has presented a more optimistic scenario, raising his target from $796 to $1,000 while maintaining an Overweight rating. The new target represents potential appreciation of 39.1% from the latest closing price.
The investment bank’s forecast is based partly on expectations that Muse could become a significant commercial product, eventually creating additional sources of high-margin revenue beyond traditional advertising.
Wells Fargo expects AI infrastructure spending and legal liabilities to constrain near-term earnings, with 2027 potentially representing a low point before greater financial contributions from Muse emerge in 2028.
Under a more optimistic scenario, the bank sees a possible valuation as high as $1,211 per share. That is an upside case rather than its principal price target.
Broader analyst expectations for 2027 include revenue of $306.4 bn, approximately 21% above the estimated 2026 level.
Consensus earnings per share estimates stand at $34.0317 for 2027, compared with $31.2129 for 2026. At Meta’s latest closing price, the 2027 forecast implies a price-to-earnings multiple of approximately 21.1.
A $1,000 share price would require a multiple of approximately 29.4 times the same projected earnings, assuming those estimates remain unchanged.
Such a valuation would require investors to assign a substantially higher premium to Meta’s expected growth and profitability.
Earnings expectations have also weakened. Ninety days before the early-October analysis, the 2027 EPS estimate stood at $34.9236. Analysts subsequently issued 39 downward revisions against seven upward revisions over the preceding 30 days.
The downward adjustments indicate that increasing expenses are already affecting expectations for future profitability.
Meta advertising revenue rises 27% as AI improves performance
Meta’s advertising business remains the principal source of revenue and operating cash flow supporting its AI investment program.
Second-quarter 2026 revenue increased 28% year over year to $60.80 bn, while advertising revenue rose 27% to $59.36 bn. Advertising impressions across the Family of Apps increased 14%, and the average price per advertisement climbed 12%.
These figures indicate that Meta generated growth through both higher advertising volumes and improved pricing.
AI-powered recommendation systems and advertising tools have contributed to stronger content engagement, more effective targeting and improved returns on advertising spending.
The company also benefited from increased user activity. Family daily active people reached 3.60 bn in June 2026, representing 3% annual growth.
Meta’s ability to increase advertising prices while expanding impressions suggests that advertiser demand remained strong despite higher costs.
Additional products are contributing to monetization. More than 1 mn businesses use Meta’s Business Agents each week, while the Advantage+ advertising platform has exceeded a $75 bn annual run rate.
Other Family of Apps revenue reached approximately $1 bn, increasing 73% year over year.
The company’s advertising performance provides a financial foundation for AI development, although revenue expansion has not translated into comparable growth in reported earnings.
Second-quarter diluted EPS declined to $6.18 from $7.14 a year earlier and missed the $7.22 analyst consensus cited in early-October reporting.
The results included $2.40 bn in legal charges and $1.18 bn in severance expenses associated with workforce reductions.
Operating income declined 8% to $18.78 bn, while operating margin fell to 31% from 43% in the corresponding period of 2025. Excluding the specified exceptional charges, operating income would have increased approximately 9%.
Meta Muse AI could become a new revenue source
Meta’s September 8 launch of Muse introduced a more direct commercial opportunity in artificial intelligence. The personal AI agent can interact with external applications to complete tasks, including sending emails, arranging travel, managing calendars, shopping and handling certain transactions.
Muse is initially available in the United States through a dedicated application and WhatsApp, with free access and paid subscriptions priced at $20 and $100 per month.
The product forms part of Chief Executive Mark Zuckerberg’s strategy to develop what Meta describes as personal superintelligence.
Early adoption has exceeded some analysts’ expectations. By early October, Muse had recorded more than 6.6 mn downloads and reached the top of application download rankings for 16 days.
Citigroup estimates that Muse could produce more than $27 bn in annual revenue by 2030, based on its potential to become a primary interface through which consumers search for information, compare products and complete purchases.
Meta has a distribution advantage through Facebook, Instagram, Messenger and WhatsApp. These established services already reach billions of users, potentially allowing the company to introduce Muse without building an entirely separate consumer audience.
This existing distribution network could reduce some customer acquisition barriers relative to AI competitors that must attract users primarily through standalone applications.
If consumers increasingly use Muse to discover products, compare prices and complete purchases, Meta could develop advertising services connected more directly to purchasing decisions.
Potential revenue sources include performance-based advertising, shopping referrals and transaction-related fees.
The commercial proposition depends on whether Meta can retain users throughout the purchasing process and establish partnerships that support transactions.
Meta’s Muse faces privacy and profitability concerns
Early adoption does not establish that Muse will become profitable.
AI agents require computing resources each time they perform tasks, and the cost of providing those services can exceed subscription revenue when usage is intensive.
Recent analysis has raised questions about whether Muse’s free and paid tiers can generate sufficient revenue to cover their operating costs.
The issue is particularly relevant because Meta’s traditional advertising model relies heavily on user data and targeting capabilities, while Muse is marketed with privacy protections that may restrict how personal information can be used commercially.
Recent industry reporting indicates that approximately one-third of travel, shopping and reservation websites block Muse, while another third impose access challenges. Amazon is among the companies restricting the agent’s access.
These restrictions could limit Muse’s usefulness as a shopping and transaction assistant, reducing its near-term commercial potential.
Muse can access sensitive information through connected email, calendar, payment and other applications. Internal testing has identified reliability problems and incidents involving inappropriate access to private data.
Meta delayed the assistant’s original launch to improve security and introduced controls governing application access, along with systems intended to monitor autonomous actions.
Continued growth will depend partly on whether consumers trust the assistant to manage personal information and complete transactions reliably.
Meta AI spending could reach $145 bn in 2026
Capital expenditure has become one of the central financial risks in Meta’s investment case. Management expects 2026 capital expenditures, including principal payments on finance leases, to reach $130–$145 bn.
Second-quarter spending on that basis totaled $31.08 bn, compared with operating cash flow of $31.86 bn. Free cash flow consequently fell to $784 mn from $8.55 bn in the corresponding quarter of 2025.
The decline occurred despite substantial revenue growth, illustrating how infrastructure investment is absorbing cash generated by the advertising business.
Meta held $90.26 bn in cash, cash equivalents and marketable securities as of June 30, 2026, providing financial resources to continue investing. The company also carried $83.66 bn in long-term debt.
Management maintains that additional computing capacity can generate positive investment returns through better recommendation systems, advertising performance and new AI products.
The financial outcome will depend on whether incremental revenue and operating efficiencies justify the cost of the infrastructure.
Wells Fargo’s longer-term projections illustrate the scale of potential spending. Its estimates contemplate capital expenditures approaching $250 bn in 2027 and operating expenses of $210–$215 bn.
These are analyst projections rather than Meta’s official guidance.
The bank has also removed $5 bn of anticipated 2027 revenue from potential data center capacity resales from its forecast, reflecting increased demand for computing resources within Meta’s own AI operations.
Meta develops Iris AI chip to reduce infrastructure costs
Meta is working to improve the economics of its AI operations by developing proprietary processors.
Its Iris chip, part of the Meta Training and Inference Accelerators program, is designed to support AI workloads and reduce reliance on external hardware suppliers.
The company planned to begin manufacturing Iris in September 2026 following successful testing. That production schedule was reported as a plan rather than independently confirmed completed manufacturing.
Meta continues purchasing substantial quantities of processors from Nvidia and AMD, while developing its own silicon through partnerships involving semiconductor specialists.
The company plans to deploy approximately 7 gigawatts of computing infrastructure during 2026 and increase total computing capacity to around 14 gigawatts in 2027.
Producing internal processors could eventually improve operating costs and reduce exposure to third-party chip pricing and supply constraints.
The immediate financial benefit remains uncertain because proprietary chips must achieve sufficient production volumes and deployment across Meta’s computing infrastructure before materially affecting overall expenses.
The economics will also depend on manufacturing efficiency, processor performance and the cost of integrating the hardware into existing data centers.
Reality Labs losses remain a financial burden
Meta’s Reality Labs division continues generating substantial operating losses while the company expands investment in AI.
Second-quarter Reality Labs revenue totaled $431 mn, against an operating loss of $4.62 bn. For the first six months of 2026, the division accumulated approximately $8.65 bn in operating losses.
Smart glasses represent one of its more commercially promising product categories, with revenue growth supported by demand for AI-enabled eyewear.
The category nevertheless faces increasing scrutiny over privacy and the possibility of recording people without their knowledge.
On October 2, Dutch optical retailer Hans Anders suspended sales of Ray-Ban Meta smart glasses in the Netherlands and Belgium amid public and political concerns about camera-equipped devices.
Other jurisdictions are considering restrictions on smart glasses in sensitive public settings, adding potential regulatory complications.
Meta continues researching augmented reality, virtual reality and alternative wearable designs, including reports of camera-free smart glasses.
These initiatives could create future commercial opportunities, but the division’s recurring losses add to the financial burden of the company’s AI infrastructure expansion.
Regulatory pressure threatens Meta’s earnings
Legal expenses and regulatory investigations are creating additional uncertainty. On October 6, the UK communications regulator Ofcom opened a formal investigation into whether Meta adequately assessed safety risks before introducing Instagram’s Instants feature in May 2026.
Ofcom is examining compliance with obligations under the Online Safety Act, including requirements to assess risks involving illegal content and potential harm to children.
Meta maintains that it conducted the necessary assessments and provided relevant information to the regulator before the feature’s introduction.
Under the legislation, serious violations can result in fines of up to £18 mn or 10% of qualifying worldwide revenue, whichever is greater.
The financial effects of existing litigation are already visible in Meta’s results. Second-quarter legal charges reached $2.40 bn, contributing to weaker operating margins. Management raised the lower end of its full-year expense forecast, bringing expected 2026 expenses to $165–$169 bn.
The company also warned that litigation involving youth-related issues could result in additional material losses. These risks complicate forecasts for future earnings even if advertising revenue and AI adoption continue growing.
Meta Q3 2026 earnings forecast and October outlook
Meta’s third-quarter earnings report will provide the next major assessment of its financial position.
As of October 11, the company had not confirmed a Q3 reporting date through its investor relations calendar. Financial market calendars indicate October 28, 2026, after the market close, as the expected date.
Management forecasts third-quarter revenue of $61–$64 bn. The guidance incorporates an anticipated foreign-exchange headwind equivalent to approximately one percentage point of year-over-year revenue growth.
The primary issue will be whether AI-driven advertising improvements continue supporting strong demand and higher average advertising prices.
Investors will also examine the relationship between capital expenditures and operating cash flow, particularly after the sharp decline in second-quarter free cash flow.
Progress in monetizing Muse, the availability of computing infrastructure, the performance of Reality Labs and potential additional litigation expenses will influence expectations for the final quarter and 2027.
Forward guidance could be particularly important given the continued downward revisions to analysts’ earnings estimates.