Overview
U.S. stocks have continued their strong rally, with the S&P 500 gaining approximately 19% over the past six months and the Nasdaq advancing 26%. Both indexes reached record highs this week, extending a period of market gains that has raised concerns about valuations and speculative investment behavior.
Warren Buffett has repeatedly warned during 2026 about the risks of investors buying stocks primarily because prices are rising rather than because underlying businesses justify their valuations.
- The S&P 500 has gained approximately 19% over six months, while the Nasdaq has risen 26%, with both indexes reaching record highs amid concerns about speculative trading.
- The S&P 500 Shiller CAPE ratio has remained above 40 since May 2026, compared with a historical average of approximately 17 and a record of 44 before the dot-com crash.
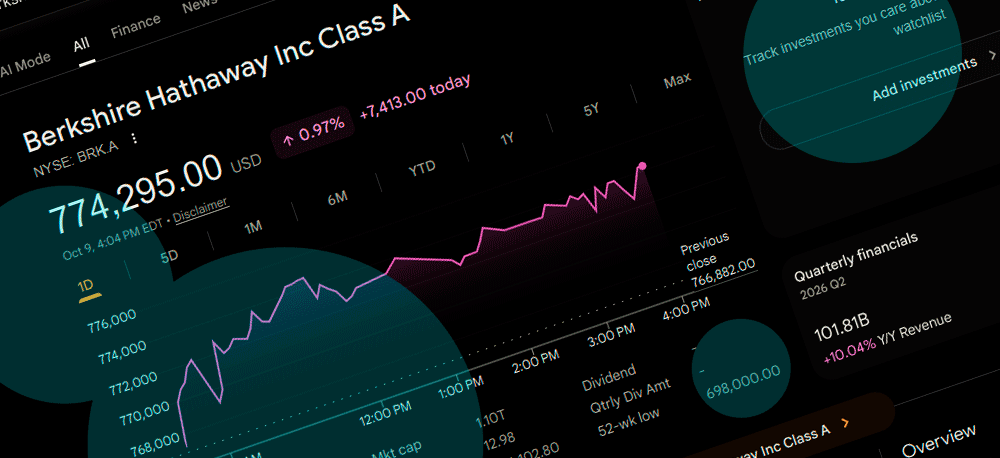
- Warren Buffett’s caution and Berkshire Hathaway’s preference for holding cash have renewed attention to earnings quality, debt levels, portfolio concentration and valuation risks.
The concern is particularly relevant as share prices advance faster than corporate earnings. Berkshire Hathaway’s decision to maintain substantial cash holdings rather than deploy more capital has also attracted attention, although its cash position alone does not establish a forecast for market performance.
One valuation measure suggests that investors are paying historically elevated prices for U.S. equities.
The S&P 500 Shiller cyclically adjusted price-to-earnings ratio, commonly known as CAPE, has remained above 40 since May 2026.
The measure compares stock prices with average inflation-adjusted earnings over the preceding 10 years, providing a longer-term assessment of valuations than conventional earnings multiples.
Its historical average is approximately 17. The ratio reached a record of 44 in late 1999, shortly before the technology-driven market bubble burst in March 2000.
A CAPE reading above 40 does not predict an imminent correction. It does indicate that investors are paying substantially more for earnings than historical norms, potentially increasing the market’s sensitivity to disappointing financial results or changes in sentiment.
The dot-com crash offers a historical comparison
The technology boom of the late 1990s provides a useful reference for understanding the risks associated with elevated valuations.
Hundreds of technology companies experienced substantial share price increases as investors placed aggressive expectations on their future growth.
When the bubble collapsed in early 2000, many businesses suffered severe losses, particularly those with weak balance sheets, unsustainable business models and limited profitability.
Companies with established earnings, manageable debt and durable competitive advantages were generally better positioned to withstand the downturn.
The distinction between share price performance and underlying business quality became particularly important once investor enthusiasm weakened.
Today’s leading technology companies may have stronger financial fundamentals than many businesses that attracted speculative investment during the dot-com era. Nevertheless, rising valuations can create risks even when the underlying companies are profitable.
Buffett’s concern centers on investor behavior that treats recent price appreciation as sufficient justification for purchasing shares, without assessing whether expected future earnings support those prices.
According to Fortune, Buffett has warned that a speculative or gambling-oriented investment culture can push valuations higher across the market, including for businesses whose financial performance does not justify the increase.
What investors should examine in their portfolios
Elevated market valuations do not necessarily require investors to liquidate their equity holdings. They do, however, provide a reason to reassess company fundamentals and portfolio risks.
Profitability is an important starting point. Businesses generating consistent earnings and operating cash flow have financial resources that can support operations during periods of weaker investor sentiment.
Companies dependent primarily on expectations of future revenue growth may be more vulnerable when market conditions deteriorate.
Debt levels also matter. Heavily leveraged businesses can face greater financial pressure when borrowing costs rise, credit availability tightens or revenue growth slows. Stronger balance sheets provide more flexibility during economic downturns.
Valuation deserves similar scrutiny. Stocks trading at high earnings multiples require substantial future growth to justify their current prices. If those expectations depend heavily on developments that have not yet materialized, investors face the possibility of significant repricing.
Portfolio concentration presents another risk. A small number of strongly performing stocks may account for a disproportionate share of portfolio gains and total exposure following a sustained rally.
Such concentration can increase vulnerability if the companies responsible for earlier gains experience simultaneous declines.
How investors can manage stock market correction risks
Attempting to identify the exact market peak is difficult, and poorly timed trading decisions can undermine long-term investment returns.
A more practical approach is to review portfolio allocations before a potential downturn rather than waiting until losses force difficult decisions.
Following six months of substantial market gains, the relative weight of equities or individual holdings may have increased beyond an investor’s intended allocation. Rebalancing can bring those exposures back into line with financial objectives and risk tolerance.
Regular investing through dollar-cost averaging offers another way to reduce dependence on market timing. Investing fixed amounts at predetermined intervals generally results in purchasing fewer shares when prices are elevated and more when prices decline.
The approach does not eliminate market risk or guarantee superior returns, but it allows investors to maintain a consistent investment schedule without needing to predict short-term price movements.
Investment horizons remain an important consideration. Funds needed within the next two or three years may be unsuitable for substantial equity exposure because a market decline could occur before the money is required.
Buffett’s warnings should therefore be understood as a caution about speculative behavior and the relationship between asset prices and underlying financial performance, rather than a prediction of an imminent stock market crash.
With the S&P 500 CAPE ratio above 40 and major indexes trading near record highs, earnings quality, financial resilience, valuation discipline and portfolio diversification remain central considerations for investors assessing their exposure to U.S. equities.