- Wells Fargo’s third-quarter net income increased 6% to $6 bn, with earnings of $1.87 per share exceeding Wall Street’s $1.85 estimate.
- Revenue rose 2% to $21.87 bn, missing expectations of $22.31 bn, while net interest income increased 5% to $12.52 bn, below the $12.63 bn forecast.
- Average loans and deposits each grew 11%, while Wealth and Investment Management revenue climbed 12% and investment banking fees increased 10%.
Wells Fargo (NYSE: WFC) reported a 6% increase in third-quarter 2026 net income to $5.95 bn, supported by stronger consumer and commercial lending, although weaker-than-expected revenue and net interest income weighed on its shares.
The fourth-largest US lender earned $1.87 per diluted share, exceeding analysts’ consensus estimate of $1.85, according to LSEG. Earnings also improved from $1.66 per share in the corresponding quarter of 2025.
Quarterly revenue increased 2% to $21.87 bn, below Wall Street’s forecast of $22.31 bn. Net interest income rose 5% year over year to $12.52 bn, missing expectations of $12.63 bn. The increase reflected higher loan and investment securities balances, fixed-rate asset repricing and growth in the bank’s Markets business.
These gains were partly offset by lower yields on floating-rate assets, higher deposit costs and a modest decline in noninterest-bearing deposits.
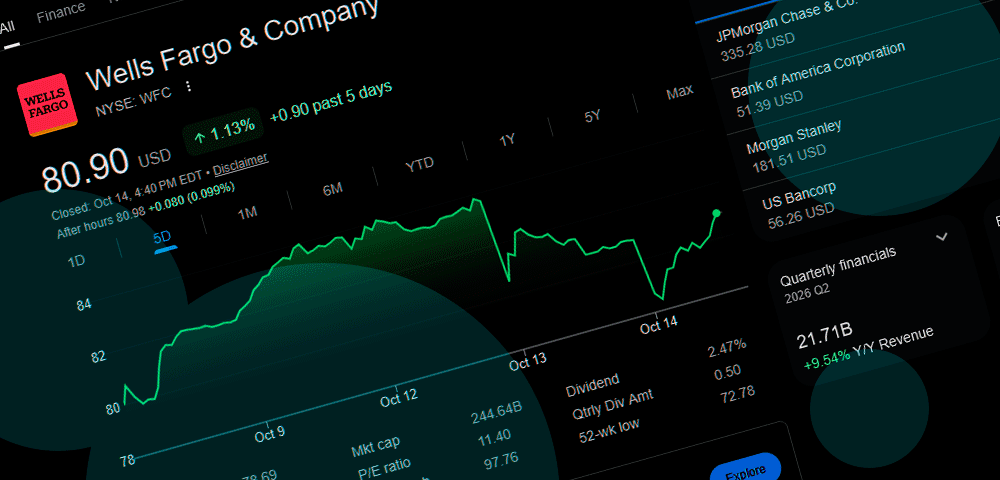
Wells Fargo shares declined approximately 1.3% following the results, as investors assessed the impact of interest rates and weaker capital markets activity on future earnings.
The results came amid mixed quarterly performances across major Wall Street banks, following a period of financial market volatility linked to the conflict in Iran, higher oil prices and a sharp selloff in global bond markets.
Chief Executive Officer Charlie Scharf warned that persistent inflation and elevated borrowing costs could affect household finances and corporate activity.
Despite those concerns, Wells Fargo reported continued expansion in lending and deposits.
Inflation and higher interest rates continue to be headwinds, and the longer they persist, the more pressure they can place on both consumers and commercial clients. While markets have been strong, an unexpected or significant movement could filter through the broader economy.
Charlie Scharf, Wells Fargo Chief Executive Officer
Average loans increased 11% year over year to $1.03 trillion, while average deposits rose 11% to $1.48 trillion.
Consumer Banking and Lending generated revenue of $10.66 bn, up 5%, while net income increased 21% to $2.76 bn.
Average consumer loans rose 4% to $342.1 bn. The bank opened more than 660,000 new credit card accounts, while automobile loan originations increased 15% compared with the previous year.
Consumer, Small and Business Banking revenue increased 7%, supported by higher deposit balances, wider deposit spreads and stronger fee income.
Auto lending revenue rose 33%, reflecting higher loan balances and improved spreads, while Home Lending revenue declined 15% because of lower mortgage servicing income and reduced loan balances.
Commercial Banking revenue increased 6% to $3.24 bn, with net income rising 3% to $1.20 bn. Average commercial loans grew 10% to $240.5 bn, while deposits increased 16% to $198.9 bn.
The division benefited from higher lending balances and deposit-related income, although its provision for credit losses increased as the loan portfolio expanded.
Corporate and Investment Banking recorded revenue of $5.01 bn, up 3% year over year, while net income declined 2% to $1.92 bn.
Investment banking revenue increased 10% to $611 mn, supported by higher merger and acquisition advisory fees, investment-grade debt underwriting and equity capital markets activity.
M&A revenue climbed 30%, while equity capital markets and investment-grade underwriting fees each increased 33%.
Investment banking revenue nevertheless declined 3% from the second quarter as market uncertainty and higher borrowing costs prompted some companies to delay fundraising and investment decisions.
Markets revenue slipped 1% year over year to $1.84 bn and fell 17% from the previous quarter.
Fixed income, currencies and commodities revenue decreased 7% to $1.26 bn, reflecting weaker trading performance across several products. Equities revenue increased 21% to $543 mn, partially offsetting the decline.
Wells Fargo has continued investing in its investment banking and markets operations, including hiring senior bankers and expanding client financing and trading capabilities.
Chief Financial Officer Mike Santomassimo said he expects net interest income to increase in the fourth quarter, supported by further loan and deposit growth and benefits from higher interest rates.
Some of those gains could be offset by the Markets business, where increased funding costs may weigh on net interest income.
Wealth and Investment Management reported revenue of $4.10 bn, up 12%, while net income increased 19% to $603 mn.
Growth was supported by higher investment advisory fees, improved market valuations and increased loan and deposit balances.
Client assets reached $2.74 trillion, representing an 11% increase from the previous year.
Wells Fargo also reported improved operating efficiency. Noninterest expenses declined 1% to $13.74 bn, reflecting cost reduction initiatives and an 8% decrease in headcount.
The bank’s efficiency ratio improved to 63%, compared with 65% a year earlier. Credit loss provisions increased to $1.03 bn from $681 mn, primarily reflecting higher reserves associated with commercial and industrial lending and automobile loans.
Net charge-offs totaled $983 mn, compared with $954 mn a year earlier. The net loan charge-off ratio improved to 0.38%, from 0.40%. Nonperforming assets declined to $7.36 bn from $7.83 bn, indicating continued improvement in parts of the bank’s credit portfolio.
Wells Fargo reported a return on tangible common equity of 16.3%, compared with 15.2% in the prior-year quarter. Its Common Equity Tier 1 capital ratio stood at 10%, while the bank repurchased 28.6 mn common shares for approximately $2.5 bn during the quarter.
The results show that loan growth and higher fee income continue to support Wells Fargo’s profitability, although the weaker-than-expected revenue figures and slower trading activity have increased attention on its fourth-quarter net interest income outlook.