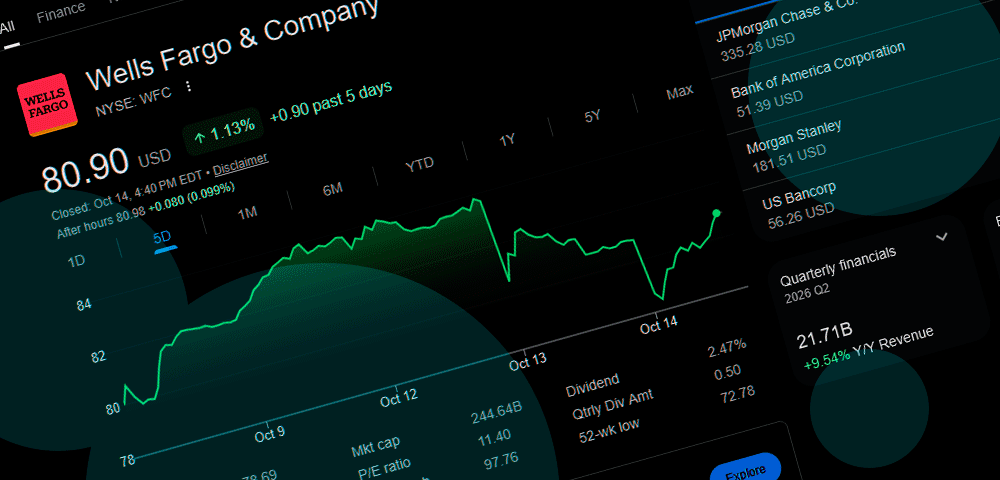
- Wells Fargo shares closed at $80.90 on October 14, while the average 12-month analyst price target of approximately $98 implies around 21% upside.
- RBC Capital Markets, Morgan Stanley, Citigroup and Keefe, Bruyette & Woods lowered their price targets following Q3 earnings but maintained their existing ratings.
- Wells Fargo reported Q3 earnings of $1.87 per share, exceeding expectations, although revenue of $21.87 bn and net interest income of $12.52 bn missed forecasts.
Wells Fargo & Company (NYSE: WFC) remains a favorable stock among Wall Street analysts despite a series of price target reductions following its third-quarter 2026 earnings report.
As of October 14, 2026, the consensus 12-month price target stood at approximately $98 per share, representing potential upside of around 21% from the closing price of $80.90.
The broader analyst consensus remained Moderate Buy, with 18 positive ratings, eight Hold recommendations and no Sell ratings.
RBC Capital Markets analyst Gerard Cassidy reduced his price target from $100 to $92 while maintaining an Outperform rating. Cassidy expects Wells Fargo to benefit from renewed balance sheet expansion after more than seven years of regulatory growth restrictions.
The bank’s total assets exceeded $2.25 trillion in Q3 2026, supporting its strategy to expand lending and improve capital efficiency. RBC maintained its earnings forecasts of $7.25 per share for 2026 and $8.10 for 2027.
- Morgan Stanley analyst Manan Gosalia lowered his target from $102 to $101 while retaining an Overweight rating, making it one of the more optimistic forecasts among the major brokerages.
- Citigroup analyst Keith Horowitz reduced his target from $90 to $88 and maintained a Neutral rating. Keefe, Bruyette & Woods cut its forecast from $94 to $90, reiterating Market Perform.
- Other recent recommendations included a $102 target from UBS with a Buy rating, while Truist Financial and TD Cowen each maintained positive recommendations with $95 targets.
- The revisions followed mixed quarterly results. Wells Fargo’s net income increased 6% year over year to $5.95 bn, while earnings per share rose 13% to $1.87, exceeding the $1.85 consensus estimate.
Revenue advanced 2% to $21.87 bn but missed expectations of $22.31 bn. Net interest income increased approximately 5% to $12.52 bn, below the anticipated $12.63 bn, as higher deposit costs and reduced yields on floating-rate assets constrained performance.
The bank nevertheless recorded 11% growth in average loans and deposits, while its efficiency ratio improved to 63% from 65% a year earlier. Return on tangible common equity reached 16.3%, approaching management’s medium-term target of 17% to 18%.
Analysts remain focused on Wells Fargo’s ability to sustain loan growth, protect net interest margins and control expenses. RBC also expects the dividend payout ratio eventually to reach 30% to 40%, with potential capital relief from proposed Basel III changes.
The current analyst forecasts suggest a positive 12-month outlook for WFC, although recent target reductions indicate more measured expectations for earnings growth. Achieving the bank’s profitability targets will depend on continued balance sheet expansion, funding costs and operating efficiency.