- El Niño reaches highest intensity category as California faces storm risks
- Home insurance claims: A 10-minute video can document property losses
- Document roof conditions and the exterior before winter storms
- Standard homeowners insurance generally excludes flood damage
- Check insurance sublimits for fallen trees, valuables and emergency repairs
- How to document damage and file an insurance claim after a storm
California homeowners are facing heightened risks of flooding, landslides and storm damage as one of the strongest El Niño events on record develops across the Pacific Ocean. Weather forecasts indicate that repeated atmospheric rivers could bring heavy rainfall, strong winds and significant snowfall to the Sierra Nevada during winter 2026-2027.
The National Oceanic and Atmospheric Administration (NOAA) classified the current El Niño as “very strong” on November 12, its highest intensity category. Only three previous events have reached this level since modern records began in 1950: 1982-1983, 1997-1998 and 2015-2016.
- NOAA has classified the 2026 El Niño as very strong, with a 60% probability of exceeding the intensity of previous major events.
- California faces increased exposure to atmospheric rivers, flooding, landslides and coastal storms, while standard homeowners insurance generally excludes flood damage.
- Insurance adjusters recommend recording a complete home inventory, documenting roof conditions and checking policy limits before storms arrive.
Insurance specialists are urging property owners to document their homes and review coverage before severe weather arrives. A smartphone video inventory, which can take approximately 10 minutes, could provide important evidence when filing a claim for damaged or destroyed property.
El Niño reaches highest intensity category as California faces storm risks
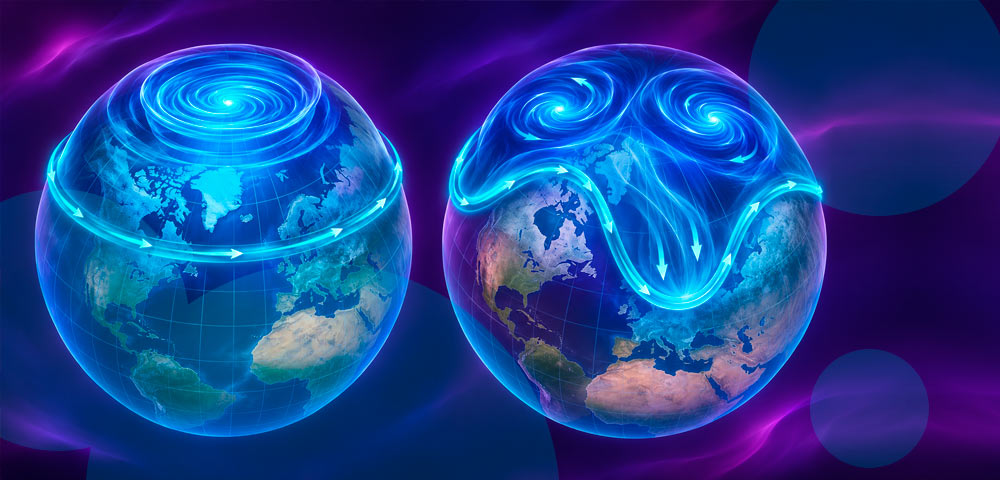
El Niño develops when surface waters in the central and eastern tropical Pacific become unusually warm, influencing atmospheric circulation and weather patterns worldwide.
According to NOAA’s Climate Prediction Center, the current event is expected to peak between late 2026 and early 2027.
NOAA noted the strongest three-month average is likely to occur during October-December or November-January.
The agency estimates a 61% probability that conditions will return to ENSO-neutral during April-June 2027, while the probability of El Niño persisting through that period is 38%.
The World Meteorological Organization expects the event to increase the risk of extreme heat, drought and heavy rainfall well into 2027.
Even after Pacific Ocean temperatures begin cooling, El Niño can continue influencing global weather through interactions with jet streams, monsoons and other atmospheric systems.
In California, forecasters warn that repeated atmospheric rivers could increase the likelihood of river flooding, flash floods and landslides.
Heavy precipitation may also bring substantial Sierra Nevada snowfall, benefiting water supplies while creating risks from winter storms and subsequent snowmelt.
Elevated coastal water levels could compound flooding during periods of high tides and strong winds.
Elsewhere in the United States, an active southern storm track could bring frequent rainfall to the Southern Plains, Southeast and mid-Atlantic regions.
The Midwest, Great Lakes and Northeast are generally expected to experience warmer conditions and below-average snowfall, although major winter storms remain possible.
NOAA’s longer-range forecast also allows for a transition to La Niña later in 2027, with a 33% probability during June-August.
Home insurance claims: A 10-minute video can document property losses
California emergency management and insurance professionals recommend creating a visual inventory of household belongings before severe weather.
Homeowners can record a continuous smartphone video while walking through each room, opening cabinets, closets and drawers, and briefly describing their possessions.
The recording should include kitchens, bedrooms, bathrooms, living areas, garages, basements and other storage spaces.
Jackie Thornhill, communications manager for the San Francisco Department of Emergency Management, said advance warnings provide an opportunity to prepare that is often unavailable before sudden disasters such as earthquakes and wildfires.
Steve Severaid, president of Greenspan Co./Adjusters International, said a narrated video inventory is sufficient as a starting point for most households.
“If you capture it on video and narrate it, that’s a good place to start,” Severaid said.
The objective is to establish what property existed before damage occurred, rather than produce a detailed written valuation of every item.
Even inexpensive household goods can represent a substantial combined replacement cost.
Severaid noted that homeowners frequently underestimate the number and value of everyday possessions, including towels, clothing and miscellaneous items stored in drawers.
A single drawer containing numerous small objects could hold belongings worth $500 to $1,000.
The California Department of Insurance recommends documenting furniture, appliances, electronics, computers, televisions, clothing, shoes, jewelry, tools, recreational equipment, collectibles and valuables.
For expensive appliances and electronics, homeowners should also record brand names, model numbers and serial numbers.
Receipts, appraisals and original packaging can help establish value, particularly for high-cost purchases. Photographs and videos may be especially important for inherited property, antiques and older belongings without surviving purchase records.
The completed inventory should be saved in cloud storage or on an external device kept away from the property.
Document roof conditions and the exterior before winter storms
Homeowners should photograph or film the exterior of their buildings, including roofing, windows, siding, fences and other potentially vulnerable structures.
Documenting roof conditions is particularly important because insurers may need evidence distinguishing recent storm damage from deterioration that occurred before the insured event.
Severaid recommends recording shingles from multiple angles to demonstrate their condition and placement before severe winds arrive.
Drone footage can also be useful when available and safely obtained.
Pre-storm images showing an intact roof can help establish whether missing shingles or other damage resulted from a subsequent weather event.
Exterior documentation may also help support claims involving fallen trees, damaged outbuildings and wind-related structural losses.
Images should be dated and stored alongside the household inventory.
Standard homeowners insurance generally excludes flood damage
One of the most significant insurance gaps facing California property owners concerns flooding.
Standard homeowners and renters policies generally do not cover damage caused by rising surface water, overflowing rivers or water entering a building from the surrounding ground.
Allison Castro Hensley, senior deputy press secretary for the California Department of Insurance, warned that consumers frequently discover this exclusion only after experiencing a flood.
Coverage depends on how water enters the property and the specific policy wording. Rain entering through a window damaged by insured wind may qualify for coverage under a homeowners policy. Water accumulating outside before flowing into a building generally requires separate flood insurance.
According to the Insurance Information Institute, only approximately 2% of Californians carry flood insurance.
Flood insurance is separate from standard homeowners coverage, and many policies have a 30-day waiting period before protection takes effect.
Property owners in flood-prone areas should review their exposure before storms develop, particularly where there is a history of river flooding, drainage problems or surface-water accumulation. The waiting period means purchasing coverage immediately before a forecast storm may not provide protection for that event.
Flood insurance also has its own coverage limits, exclusions and deductibles, making it important to understand what buildings and personal property are insured.
Check insurance sublimits for fallen trees, valuables and emergency repairs
In addition to flood exclusions, homeowners should review sublimits that restrict how much their insurer will pay for specific types of property or services.
Policyholders should check whether their coverage includes debris removal, tree removal, emergency repairs and additional living expenses. Jewelry, fine art, collectibles and cash may also be subject to relatively low limits under standard policies.
Separate endorsements or scheduled personal property coverage may be appropriate for possessions whose value exceeds those limits.
How to document damage and file an insurance claim after a storm
After severe weather, homeowners should document damage as soon as it is safe to access the property.
Photographs and videos should capture structural damage, affected rooms, damaged belongings and any visible evidence of the event.
Insurance adjusters recommend retaining damaged materials until the insurer has had an opportunity to inspect them, unless removal is necessary for safety or to prevent further damage.
Water-damaged furniture, broken roof materials and other affected property can be moved to a secure location when practical.
Homeowners should notify their insurance company promptly and maintain written records of claims communications.
Receipts should be retained for emergency repairs, temporary accommodation, cleanup supplies and other expenses related to the loss.
The California Department of Insurance recommends keeping copies of correspondence, claim documents and payment records throughout the process.
Policyholders who need assistance with insurance questions or claims disputes can contact the department at 800-927-4357.
With El Niño expected to remain influential through the coming winter, reviewing coverage and maintaining an accurate pre-loss property record can help homeowners identify insurance gaps and substantiate claims if severe weather causes damage.