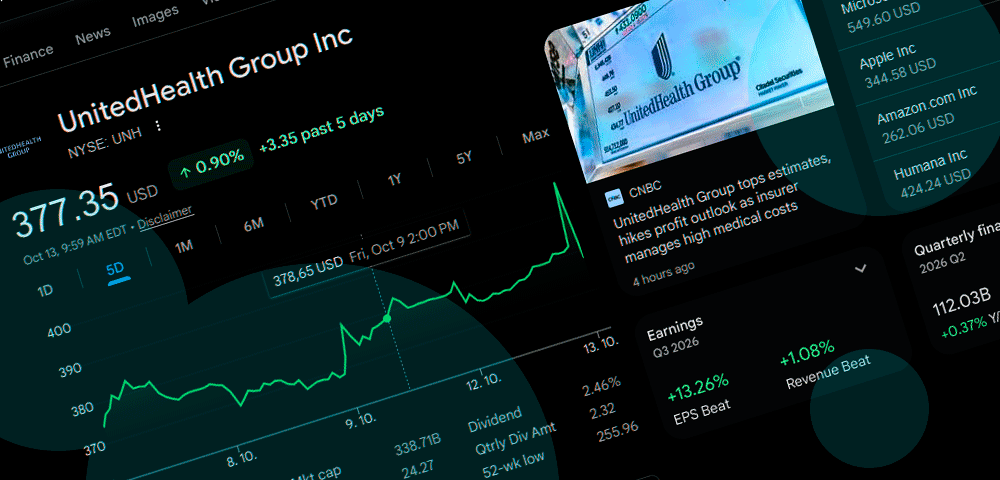
- UnitedHealth Group (NYSE: UNH) reported Q3 2026 adjusted earnings of $4.69 per share, beating the $4.14 consensus, and raised its full-year adjusted EPS guidance to at least $20.50.
- The medical care ratio improved to 88.4% from 89.9% a year earlier, supporting stronger profitability despite continued pressure from Medicare Advantage costs and declining membership.
- Wall Street’s average 12-month price target stands at $480.60, suggesting approximately 25% upside from early October 13 trading levels. Management indicated that 2027 earnings growth could exceed current analyst expectations.
UnitedHealth Group (NYSE: UNH) shares advanced following its October 13, 2026, earnings release as the largest U.S. private health insurer delivered stronger-than-expected third-quarter profits and raised its annual outlook for the third time this year.
The stock traded around $383–$387 in early trading, compared with its October 12 closing price of $378.52. The results provided further evidence of a recovery after two years of elevated medical costs, restructuring and pressure on its Medicare Advantage business.
Third-quarter revenue reached $112.69 bn, exceeding the $111.40 bn LSEG consensus, although it declined slightly from $113.16 bn a year earlier.
Net income increased to $4.11 bn, or $4.56 per share, from $2.35 bn, or $2.59 per share, in the prior-year quarter. Adjusted EPS rose to $4.69 from $2.92, comfortably ahead of Wall Street’s $4.14 estimate.
Operating earnings increased to $6.6 bn from $4.3 bn, while operating cash flow reached $5.1 bn.
The company now expects adjusted 2026 earnings of at least $20.50 per share, compared with its previous forecast of $19.50–$20.
UnitedHealth’s medical cost ratio improves to 88.4%
The most consequential development was a reduction in the medical care ratio to 88.4%, compared with 89.9% a year earlier and analysts’ expectations of 89.9%.
The improvement reflects revised insurance pricing, benefit adjustments and efforts to manage healthcare utilization. It also benefited from $610 mn in favorable reserve development related to earlier 2026 medical services, a factor investors should distinguish from recurring cost savings.
CFO Wayne DeVeydt cautioned that medical expenses remain elevated compared with historical levels.
The federal independent dispute resolution process under the No Surprises Act is adding at least one percentage point to the company’s medical costs, according to DeVeydt. Hospital inpatient services and expensive specialty medications remain additional sources of pressure.
UnitedHealthcare generated $86.3 bn in revenue and $2.8 bn in operating earnings. Membership declined to 48.3 mn, reflecting the company’s decision to reduce exposure to less profitable insurance contracts.
Medicare Advantage membership has fallen by approximately 935,000 since the end of 2025.
Optum reported $66.9 bn in revenue and $3.7 bn in operating earnings, supported by improved performance in clinical care operations.
Management is also expanding value-based care arrangements and AI-assisted administrative tools. Acute hospital admissions declined 15% year over year through the third quarter, while home health admissions increased 10%.
These changes may help reduce treatment costs, although their longer-term financial contribution remains dependent on execution.
UnitedHealth stock price targets and 2027 earnings forecast
Wall Street analysts maintain a consensus Buy rating on UnitedHealth, with an average 12-month price target of $480.60 across 26 analysts surveyed by S&P Global Market Intelligence.
Individual forecasts include UBS at $490, RBC Capital Markets at $478, Piper Sandler at $463 and TD Cowen at $402.
The broader analyst target range extends from $380 to $529, reflecting differing assumptions about medical expenses, membership growth and the recovery in operating margins.
UnitedHealth’s preliminary 2027 earnings outlook may be more significant than the quarterly earnings beat.
DeVeydt suggested that earnings growth at the lower end of the company’s long-term 13%–16% objective represented a reasonable starting point for next year.
Applying 13% growth to the updated 2026 adjusted EPS guidance of $20.50 produces approximately $23.17 per share for 2027, above the existing Wall Street consensus of $22.61.
At an early-session share price of approximately $384, UnitedHealth trades at about 18.7 times its minimum projected 2026 adjusted earnings and 16.6 times the illustrative 2027 figure.
That valuation leaves room for appreciation if earnings recover as management anticipates. Risks remain substantial, including medical inflation, changes in Medicare Advantage reimbursement, declining membership and weaker quality ratings that could affect future bonus payments.
For the next 12 months, analyst targets around $463–$490 imply approximately 21%–28% upside from $384, provided UnitedHealth continues improving profitability and delivers the earnings growth management has outlined.
The third-quarter results support a more constructive earnings outlook, but the critical measure will be whether UnitedHealth can sustain lower medical cost ratios without relying heavily on favorable reserve adjustments or further reductions in membership.