Follow Beinsure
- SoundHound AI Stock Forecast: Analyst Targets and Ratings
- November 5 Earnings: Revenue Growth Versus Profitability
- Second-Quarter Results Show Improving Margins
- LivePerson Acquisition Reshapes the Growth Outlook
- Voice AI Expansion Supports Demand Across Industries
- SOUN Valuation Depends on Long-Term Margin Expansion
- What Could Move SoundHound AI Stock After Earnings?
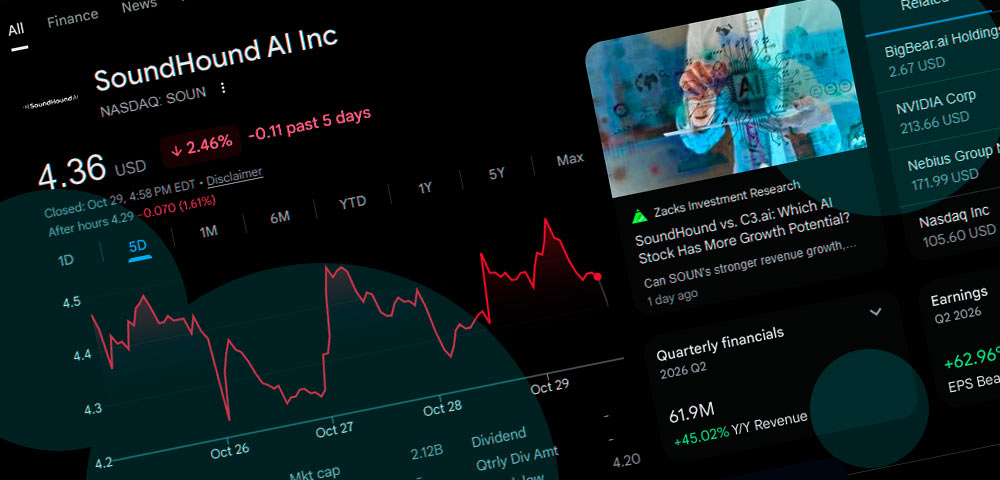
SoundHound AI (NASDAQ: SOUN) shares closed at $4.36 on October 29, 2026, down 1.8% for the session and trading close to their 52-week low of $4.20. The decline contrasts with Wall Street’s broadly positive ratings, although recent analyst revisions show growing caution about the company’s ability to translate rapid revenue expansion into sustainable earnings.
The next test comes on November 5, when SoundHound reports third-quarter results after the US market closes. Investors will be assessing not only demand for its conversational AI technology but also the financial implications of its recently completed acquisition of LivePerson.
- Eight analysts give SoundHound AI a consensus Buy rating, with an average 12-month price target of $12.57, implying approximately 188% upside from its October 29 closing price.
- Third-quarter revenue is forecast to rise nearly 50%, but Zacks expects a wider adjusted loss per share. Positive estimate revisions suggest some optimism ahead of the November 5 report.
- The September acquisition expands SoundHound’s enterprise business but raises questions about organic growth, integration costs, share dilution and the path to profitability.
The transaction has substantially expanded SoundHound’s potential customer base. It has also complicated comparisons between historical results, current earnings estimates and management’s longer-term growth ambitions.
SoundHound AI Stock Forecast: Analyst Targets and Ratings
Consensus data compiled by S&P Global Market Intelligence show six Buy ratings and two Hold ratings. The median 12-month price target is $12, with forecasts ranging from $6 to $17.
The substantial gap between those projections and the current share price reflects both expectations for long-term growth and the stock’s steep decline. However, many published targets predate the latest selloff, and recent revisions have generally moved downward.
Piper Sandler represents the more cautious side of Wall Street. Analyst James Fish lowered his target from $7 to $6 on September 22 while maintaining a Neutral rating.
The firm’s concerns center on the acquisition of LivePerson, whose revenue base is larger than SoundHound’s legacy operations but faces structural pressure. Piper models a 20% annual revenue decline at LivePerson and expects cost savings to build toward $75 mn by 2028.
That assessment raises an important distinction between reported growth and organic expansion. Acquiring a larger business increases revenue immediately, but the combined company’s growth rate could weaken if the acquired customer base continues contracting.
Daniel Ives initiated coverage at Yorkville Ives in October with a Hold rating and a $6.50 target. His assessment recognizes SoundHound’s opportunity in enterprise voice AI but identifies the migration of LivePerson customers to the OASYS platform as a key execution challenge.
Ives also highlighted the company’s reliance on stock-funded acquisitions and continuing operating losses.
The more optimistic group includes Ladenburg Thalmann, which maintained a Buy rating and $16 target in August, and Cantor Fitzgerald, which reiterated its Buy recommendation and $15 objective following second-quarter results.
Northland Capital Markets and Wedbush have maintained positive ratings with $12 targets.
D.A. Davidson occupies a more measured position within the bullish camp. Analyst Gil Luria reduced his objective from $12 to $10 on August 6 but retained a Buy rating, citing strong demand for OASYS and major customer wins as support for the company’s revenue outlook.
The disagreement is therefore less about whether SoundHound has a market for its technology and more about the earnings quality, integration requirements and valuation that should accompany its expansion.
November 5 Earnings: Revenue Growth Versus Profitability
Zacks expects SoundHound to report third-quarter revenue of $63.02 mn, representing 49.9% growth from the corresponding period in 2025. Its consensus adjusted earnings estimate is a loss of $0.06 per share, compared with a loss of $0.03 a year earlier.
Earnings expectations are not uniform across financial-data providers. Other estimates indicate revenue of approximately $61.71 mn and a loss approaching $0.13 per share. Differences in analyst coverage and accounting methodology make it important to distinguish adjusted earnings forecasts from GAAP projections.
Recent revisions provide a somewhat more encouraging signal.
The Zacks consensus EPS estimate has improved by 2.78% over the past 30 days. Its Earnings ESP stands at +33.33%, while SoundHound carries a Zacks Rank of #3, or Hold.
The positive ESP suggests that more recent earnings forecasts are less negative than the broader consensus. SoundHound has exceeded consensus EPS expectations in two of its previous four quarters, although its record does not establish a consistent pattern of positive surprises.
A revenue beat would be more significant if accompanied by lower operating losses and evidence that the company’s expanding enterprise business is improving profitability.
Management’s comments about LivePerson will also matter because the acquisition closed during the quarter, potentially affecting the comparability of reported and forecast revenue.
Second-Quarter Results Show Improving Margins
SoundHound reported record revenue of $61.9 mn in the second quarter, up 45% year over year. Its GAAP gross margin improved to 45.1% from 39.0%, while its adjusted gross margin remained stable at 58.4%.
The improvement in reported margins indicates better cost absorption or a more favorable accounting comparison, while the unchanged adjusted figure suggests that underlying gross profitability has not yet accelerated at the same rate.
The company narrowed its GAAP net loss to $42.8 mn from $74.7 mn a year earlier. Adjusted EBITDA improved to a loss of $9.6 mn from $14.3 mn.
These results demonstrated progress in operating efficiency, but SoundHound remained unprofitable under both accounting measures.
The company’s first-half operating cash outflow also increased to approximately $60 mn from $43.7 mn in the prior-year period. That cash-flow trend illustrates the continuing cost of expanding the business despite improved quarterly earnings metrics.
SoundHound ended June with $203 mn in cash and cash equivalents and no debt. However, the subsequent LivePerson transaction changed the group’s financial structure, making an updated cash position particularly important in the November report.
LivePerson Acquisition Reshapes the Growth Outlook
SoundHound completed its acquisition of LivePerson on September 4, extending its conversational AI capabilities beyond voice interactions into digital messaging, customer service and enterprise communications.
The combined company serves customers that include 25 of the Fortune 100 and holds more than 750 patents.
SoundHound plans to integrate LivePerson’s digital engagement technology into OASYS, allowing enterprise customers to manage voice, web, mobile, messaging and other interactions through a unified platform.
The commercial opportunity lies in selling additional AI services to established LivePerson customers while expanding SoundHound’s existing relationships into digital customer engagement.
Management has identified an opportunity to generate more than $500 mn in future revenue from the combined existing customer base. That figure represents a commercial ambition rather than contracted revenue or formal annual guidance.
Before completing the transaction, SoundHound raised its 2026 revenue guidance to $230 mn-$260 mn, with plans to update the outlook following the acquisition.
The company had also indicated that combined revenue could reach at least $350 mn-$400 mn in 2027, including a contribution of at least $100 mn from LivePerson’s customers.
Separately, aggregated analyst projections indicate approximately $293.7 mn in revenue for 2026 and $390.2 mn for 2027. Those estimates should not be compared directly with the pre-acquisition guidance because they may incorporate different assumptions about consolidation and business performance.
In settling LivePerson’s secured debt, SoundHound issued approximately 36.9 million shares of its common stock to noteholders and paid about $5.85 mn in cash. Additional shares were issued as consideration to former LivePerson shareholders.
Although the transaction eliminated LivePerson’s outstanding secured debt, the larger share base means that growth in total earnings will not necessarily translate into equivalent improvement in earnings per share.
John Collins, formerly a senior executive at LivePerson, became SoundHound’s chief financial officer following the acquisition. His responsibilities include managing integration, controlling costs and accelerating the move toward sustainable profitability.
Voice AI Expansion Supports Demand Across Industries
SoundHound’s underlying growth prospects extend beyond the acquisition. The company has expanded OASYS adoption among enterprise customers and introduced OASYS Edge, allowing manufacturers to deploy conversational AI capabilities directly on vehicles and connected devices rather than relying exclusively on cloud processing.
In September, SoundHound announced the deployment of its generative AI voice technology in the Kia Sorento in India.
The automotive rollout adds to existing relationships with manufacturers including Hyundai and Stellantis, where SoundHound provides voice assistance and conversational technology.
The company has also expanded in restaurants, healthcare and financial services. Its restaurant customers include Five Guys, IHOP and Jersey Mike’s, while recent healthcare contracts and enterprise partnerships provide opportunities for automated customer service and transaction processing.
A new Latin American partnership announced during the second quarter included an initial eight-figure agreement spanning more than 20 countries.
Competition remains substantial, particularly from large technology companies developing enterprise AI agents and from established customer-service software providers.
SoundHound must demonstrate that its proprietary technology and industry-specific applications can sustain pricing and customer retention as conversational AI becomes more widely available.
SOUN Valuation Depends on Long-Term Margin Expansion
At a quoted market capitalization of approximately $1.9 bn and trailing revenue of $203.2 mn, SoundHound trades at roughly nine times historical sales.
The valuation remains demanding for a company generating negative operating cash flow, despite the sharp decline in its share price.
Longer-term models assume that revenue growth and improving margins will eventually support substantially higher earnings.
A Simply Wall St valuation scenario projects revenue reaching $463.8 mn by 2029, based on annual growth of approximately 31.7%.
The model also illustrates a potential improvement from a trailing net loss of $136.8 mn to annual earnings of $54.4 mn, a swing of roughly $191.2 mn.
Crucially, that future profit figure is a modeled scenario, not a confirmed analyst earnings forecast. It assumes SoundHound’s net profit margin reaches approximately 11.7%, broadly in line with the US software industry’s average used in the model.
The valuation also relies on a future price-to-earnings multiple of approximately 157 times, a discount rate of 9.1% and annual share-count growth of about 5.7%.
Such assumptions illustrate the sensitivity of SoundHound’s estimated fair value to long-term profitability and dilution.
Conversely, faster enterprise adoption, stronger recurring revenue and successful integration could support higher earnings than current operating results suggest.
The central valuation risk is that revenue growth may arrive well before the cash generation needed to justify optimistic price targets.
What Could Move SoundHound AI Stock After Earnings?
The November 5 report will provide the first quarterly update following the LivePerson acquisition. Three developments are particularly important for the share-price outlook.
- First, investors will assess whether the company can maintain strong underlying revenue growth as the acquired business enters the consolidated financial statements.
- Second, they will examine whether adjusted EBITDA losses continue narrowing and whether gross margins remain stable despite changes in product and acquisition mix.
- Third, updated financial guidance should clarify the relationship between SoundHound’s existing operations, LivePerson’s revenue contribution and the cost savings required to make the combined business profitable.
An earnings beat accompanied by stronger margins and credible integration targets could support a recovery from the stock’s recent lows.
However, higher reported revenue driven primarily by acquisition accounting, without progress in organic growth or cash generation, would provide a weaker foundation for a sustained revaluation.
With SoundHound trading near its annual low, the November earnings release will test whether Wall Street’s bullish forecasts are supported by improving operating economics or remain dependent on an ambitious long-term growth scenario.