Follow Beinsure
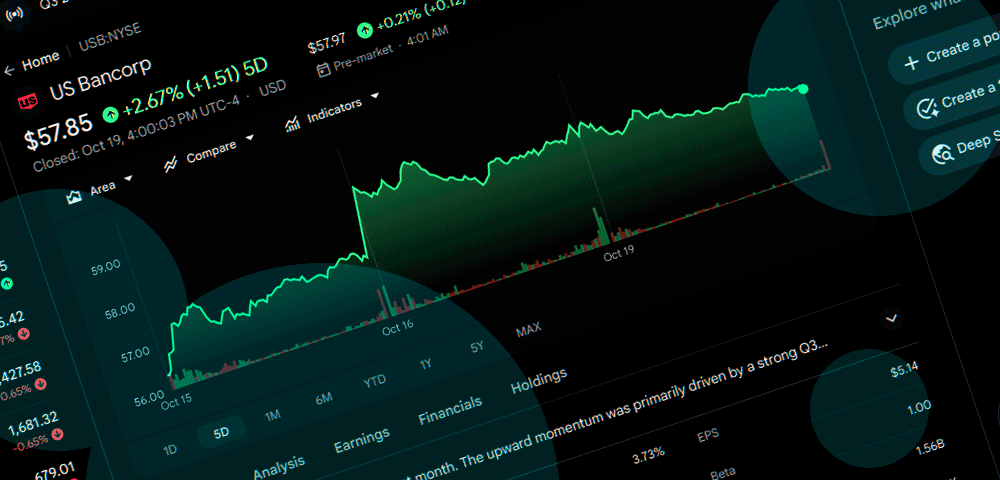
U.S. Bancorp (NYSE: USB) is attracting renewed attention from Wall Street following stronger third-quarter earnings, higher lending volumes and improved operating efficiency. Analysts remain broadly positive about the bank’s earnings prospects, although several firms have reduced their price targets because of valuation and capital market conditions.
USB shares closed at $57.85 on October 19, 2026, down 1.5% for the session, after gaining 2.33% on October 16. The stock remains approximately 12.5% below its 52-week high of $66.08, reached on August 17.
- U.S. Bancorp reported record Q3 2026 revenue of $7.97 bn, up 8.7% year over year, while net income increased 10% to $2.20 bn and diluted EPS reached $1.34.
- Wall Street’s consensus rating is Buy, with an average 12-month price target of $68.50, implying 18.4% upside from the October 19 closing price. Individual analyst targets range from $61 to $76.
- Bank of America raised its price target to $68, Oppenheimer increased its target to $73, while Citi and Goldman Sachs lowered theirs to $70 and $61, respectively. USB offers an annualized dividend yield of approximately 3.73%.
According to S&P Global Market Intelligence data compiled by Stock Analysis, 24 analysts covering U.S. Bancorp have an average 12-month price target of $68.50, with a median forecast of $68. The highest target is $76, and the lowest is $61.
The consensus implies approximately 18.4% price appreciation from the latest closing price, excluding dividends. Of the 24 analysts, 13 assign Strong Buy ratings, three recommend Buy and eight rate the shares Hold. None currently recommend selling.
U.S. Bancorp analyst price targets for October 2026
The latest analyst revisions followed the bank’s October 15 earnings announcement, with several major investment banks updating their financial models and valuation assumptions.
Ebrahim Poonawala at Bank of America Securities raised his USB price target from $67 to $68 on October 19 while maintaining a Buy rating. The firm cited lower credit provisions, stronger earnings and another increase in management’s 2026 guidance. Bank of America considers the bank’s operational turnaround to be progressing.
Ben Gerlinger at Citi reduced his target from $72 to $70 while retaining a Buy recommendation. Citi described the third-quarter results as strong but adjusted its valuation following changes to its cost-of-equity assumptions.
Chris Kotowski at Oppenheimer raised his target from $72 to $73 on October 16 and maintained an Outperform rating. The revision followed reported earnings of $1.34 per share, compared with Oppenheimer’s $1.24 estimate and the $1.32 market consensus.
Other recent analyst forecasts include Wells Fargo’s Mike Mayo at $69 with a Buy-equivalent recommendation, Barclays’ Jason Goldberg at $75 with a Buy-equivalent rating, and Morgan Stanley’s Manan Gosalia at $68 with an Equal Weight-equivalent recommendation.
- John Pancari at Evercore ISI raised his target from $65 to $67, maintaining a positive rating. Christopher McGratty at Keefe, Bruyette & Woods maintained a neutral stance with a $66 target.
- Gerard Cassidy at RBC Capital Markets lowered his target from $68 to $65 while retaining an Outperform rating. RBC acknowledged improving operating trends and opportunities for continued revenue growth through existing investments and the integration of Union Bank.
- Goldman Sachs analyst Richard Ramsden lowered his target from $64 to $61 on October 15 while maintaining a Neutral recommendation.
Goldman viewed U.S. Bancorp’s operating performance positively, noting that third-quarter core return on tangible common equity reached 20.1%, approximately 140 basis points above market expectations. The firm nevertheless considered the improvement in full-year guidance largely reflected in the share price.
These forecasts indicate a generally positive earnings outlook, but analysts differ over how much future improvement is already incorporated into USB’s valuation.
U.S. Bancorp Q3 2026 earnings support higher forecasts
U.S. Bancorp reported record third-quarter revenue of $7.97 bn, an increase of approximately 8.7% from a year earlier. Net income rose 10% to $2.20 bn, while diluted earnings per share increased 9.8% to $1.34.
Net interest income grew 5.6% year over year, supported by lending growth and higher asset yields. Fee revenue increased 14.9%, reflecting stronger contributions from several business lines.
The bank’s net interest margin improved to 2.84%, up nine basis points from a year earlier and five basis points from the preceding quarter.
Average loans increased 8% year over year and 1% sequentially, while average deposits rose 2.9% from the previous year and 2.2% from the second quarter.
Operating efficiency improved. The efficiency ratio declined to 55.9%, and positive operating leverage reached 240 basis points compared with the corresponding period in 2025.
Capital markets operations made a substantial contribution following the integration of BTIG, which U.S. Bancorp acquired earlier in 2026.
The bank reported a 69.3% year-over-year increase in capital markets revenue, including a full quarter of BTIG results. Its payments businesses recorded combined revenue growth of 6.5%.
Credit performance also improved, with the net charge-off ratio declining to 0.51%, compared with 0.56% a year earlier.
The Common Equity Tier 1 capital ratio stood at 10.8% at September 30, 2026, providing an important measure of the bank’s capacity to absorb potential losses.
U.S. Bancorp earnings forecasts for 2026 and 2027
Management raised its full-year 2026 revenue growth guidance to 8% to 9%, compared with the previous range of 5% to 7%, according to the company’s third-quarter earnings call summary.
The bank also increased its expected positive operating leverage to approximately 300 basis points from the previous 200-basis-point target.
For the fourth quarter, management indicated expectations of 6% to 7% growth in net interest income, 13% to 14% growth in fee revenue and approximately 8% growth in expenses.
U.S. Bancorp also outlined a path toward a 3% net interest margin in 2027, supported by asset repricing and improvements in its funding mix.
Analyst forecasts compiled from S&P Global Market Intelligence indicate expected 2026 revenue of approximately $31.08 bn, compared with $28.66 bn in the corresponding 2025 forecasting series.
Consensus adjusted earnings per share for 2026 stand at $5.35, representing expected growth of 15.8%. For 2027, analysts forecast revenue of approximately $33.33 bn, an increase of 7.3%, and adjusted EPS of $5.83, up approximately 9%.
These projections imply continued earnings growth, although at a slower rate than expected for 2026. They remain dependent on lending demand, funding costs, credit performance and the bank’s ability to control expenses.
USB stock valuation and dividend yield
At the October 19 closing price of $57.85, U.S. Bancorp trades at approximately 10.8 times projected 2026 adjusted earnings of $5.35 per share.
Using the 2027 consensus EPS estimate of $5.83, the multiple declines to approximately 9.9 times earnings, assuming no change in the share price.
The forward 2026 earnings multiple corresponds to an implied earnings yield of approximately 9.2%.
That figure should not be confused with the return shareholders receive in cash. It represents projected accounting earnings relative to the current share price and remains exposed to credit losses, operating expenses and economic conditions.
U.S. Bancorp declared a quarterly common dividend of $0.54 per share on September 8, representing an increase of 3.8% from the previous quarterly payment.
The dividend was payable on October 15 to shareholders of record on September 30. The new quarterly rate is equivalent to $2.16 annually.
At $57.85 per share, the annualized dividend yield is approximately 3.73%.
The quarterly dividend represents approximately 40.3% of third-quarter diluted earnings per share. This relatively moderate payout ratio leaves earnings available for retained capital, investment and other shareholder distributions.
For income investors, US Treasury securities provide an alternative. The US Treasury’s 10-year constant-maturity yield stood at 5.15% on October 19, approximately 1.42 percentage points above USB’s dividend yield.
USB therefore offers a lower current cash yield than the Treasury benchmark. Its potential additional return comes from dividend growth and share price appreciation, neither of which is guaranteed.
What could influence USB shares through 2027?
U.S. Bancorp’s investment outlook depends primarily on whether earnings growth can continue without a corresponding deterioration in credit quality or capital strength.
Loan growth remains a positive factor. The 8% annual increase in average lending during the third quarter indicates continued demand among businesses and consumers.
Fee income provides another source of earnings growth, particularly following the BTIG acquisition and expansion of the bank’s payments operations.
Rising revenue and a lower efficiency ratio could support additional profitability if expenses remain controlled. The principal risks include higher funding costs, a potential increase in loan defaults and changes in interest rates that could narrow lending margins. Competition for deposits and the economic effects of sustained high borrowing costs also remain relevant.
Credit provisions deserve particular attention. Although the net charge-off ratio improved during the third quarter, future losses could reduce earnings and restrict capital distributions.
Analyst revisions also demonstrate that stronger financial results do not necessarily produce higher share price targets. Goldman Sachs and Citi lowered their forecasts despite acknowledging favorable operating performance, partly because of valuation assumptions.
The current analyst consensus of $68.50 implies 18.4% potential appreciation over the next 12 months, while the most conservative published target of $61 suggests approximately 5.4% upside from the October 19 close.
At the upper end, the $76 target represents potential appreciation of approximately 31.4%.
The consensus depends on U.S. Bancorp delivering its earnings projections while maintaining credit quality and capital strength. Its 2027 adjusted EPS forecast of $5.83 and management’s targeted improvement in net interest margin provide measurable benchmarks for assessing that outlook.
The stock’s 3.73% dividend yield adds an income component, but with 10-year Treasury yields above 5%, USB’s valuation case rests more heavily on continued earnings growth and the potential for capital appreciation than on its current cash payout alone.