- How Lloyd’s evolved from marine insurance to specialty risks
- Lloyd’s syndicate model and specialist underwriting
- How Lloyd’s chain of security protects insurance claims
- Lloyd’s global licensing and international insurance network
- Central governance and oversight of the Lloyd’s market
- Lloyd’s innovation strategy and digital transformation
- Lloyd’s role in global finance and alternative risk transfer
Lloyd’s of London has developed from a maritime insurance marketplace into a global platform for specialist risk transfer, combining syndicate underwriting, institutional capital and international market access.
How Lloyd’s institutional structure supports underwriting across marine, aviation, energy, cyber and other complex insurance classes, while allowing participants to share exposures that individual insurers may be unwilling or unable to assume independently.
Unlike a conventional insurance company, Lloyd’s operates as a marketplace where underwriting syndicates accept risks on behalf of their capital providers. Lloyd’s Corporation oversees the market, maintains central infrastructure and establishes standards but does not itself underwrite insurance policies.
Key highlights
- Lloyd’s of London combines specialist underwriting, shared risk participation and access to more than 200 jurisdictions, allowing insurers and capital providers to cover complex international exposures.
- Its three-layer chain of security includes syndicate assets, Funds at Lloyd’s and the Central Fund, providing financial protection for valid insurance claims.
- Lloyd’s continues to expand its technology and innovation capabilities through digital placement, the Lloyd’s Lab accelerator, the Innovation (ICX) class and insurance-linked securities structures.
The market is adapting its established operating model through digital placement systems, innovation programs and structures that connect traditional underwriting with alternative capital.
How Lloyd’s evolved from marine insurance to specialty risks
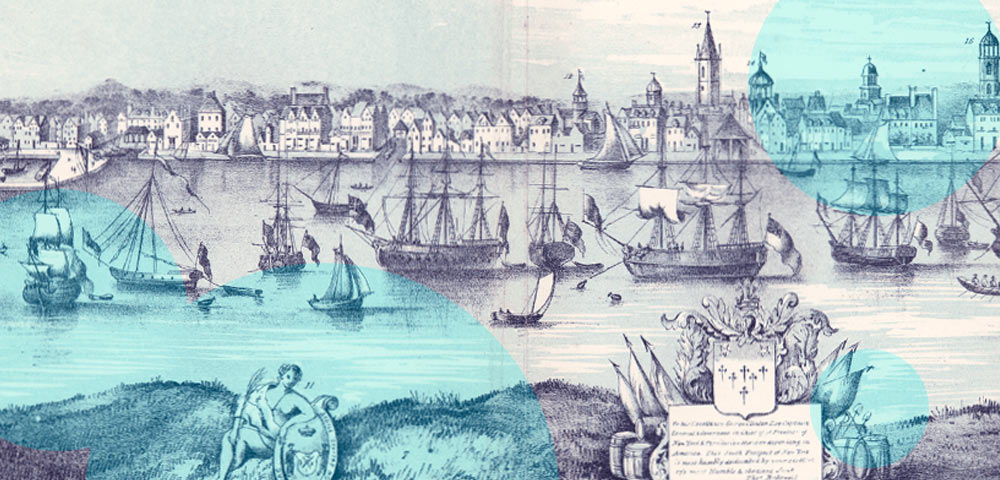
Lloyd’s originated in the late 17th century at the London coffee house operated by Edward Lloyd, which became a meeting place for maritime merchants, shipowners and captains.
Participants exchanged information about shipping movements, trade and maritime hazards. The coffee house subsequently developed into a venue where underwriters assessed risks and arranged marine insurance coverage.
In 1734, Lloyd’s began publishing Lloyd’s List, a shipping news publication that supplied information to maritime businesses and insurance underwriters.
The marketplace became a formally established institution in 1871 under a special Act of Parliament. Its development was supported by direct negotiations between brokers and underwriters, the ability to distribute large risks among multiple participants and access to international insurance markets (see how Record Global Reinsurance Capacity Turns Capital into Growth Ahead of 2027).
These characteristics allowed Lloyd’s to expand beyond marine coverage into aerospace, energy, political risk, cyber insurance and other specialist classes.
Historically, the market has underwritten unconventional exposures, including the Titanic, space exploration missions and insurance associated with celebrity body parts.
Today, Lloyd’s continues to provide capacity for risks that conventional insurers may find difficult to assess or accommodate, particularly where exposures are unusual, emerging or financially substantial.
Conning notes that Lloyd’s ability to transfer complex risks has supported international trade and investment since its maritime origins.
Lloyd’s syndicate model and specialist underwriting
The syndicate structure is central to Lloyd’s operating model. Managing agents assemble underwriting teams that include insurance specialists, claims professionals, actuaries and analysts (see Reinsurers Remain Profitable Despite Softer Pricing and Rising Loss Risks). Individual syndicates can concentrate on particular industries, insurance classes or highly specialized exposures.
Examples include marine cargo transported through conflict zones, performance guarantees associated with renewable energy projects and cyber liability protection for multinational companies.
This specialization allows syndicates to develop technical expertise in risks that require detailed assessment and tailored policy terms.
Lloyd’s also uses subscription placement to distribute large or complex insurance exposures across multiple syndicates. Rather than requiring a single insurer to accept an entire risk, several syndicates can participate, each underwriting an agreed proportion.
| Lloyd’s market feature | Function |
|---|---|
| Specialist syndicates | Underwrite defined classes of insurance risk using dedicated technical expertise |
| Managing agents | Manage underwriting operations, claims, actuarial functions and specialist teams |
| Subscription placement | Distributes large or complex exposures among participating syndicates |
| Central marketplace | Connects brokers, underwriters and capital providers |
| Global trading rights | Support insurance placements across international markets |
| Digital placement | Supplements traditional negotiations and underwriting processes |
The subscription model distributes potential losses among participating syndicates and allows different sources of capital to support the same insurance placement. It also gives corporate, private and institutional investors opportunities to participate in underwriting according to their risk appetites.
Re/insurance brokers can approach specialist syndicates within the same marketplace rather than negotiate separately with multiple insurers. The physical underwriting room in London remains part of this process, supported increasingly by digital placement technology.
Direct negotiations can accelerate underwriting decisions, particularly where complex policies require agreement between several participants.
How Lloyd’s chain of security protects insurance claims
Lloyd’s uses a three-layer capital structure known as the chain of security, designed to ensure that valid insurance claims can be paid. The arrangement combines resources held by individual syndicates with additional capital provided by members and a central market fund.
| Capital layer | Financial resources | Purpose |
|---|---|---|
| First layer: Syndicate assets | Premiums, reserves and other assets held at syndicate level | Meet claims arising from business underwritten by the syndicate |
| Second layer: Funds at Lloyd’s | Additional capital deposited by underwriting members | Provide financial support when syndicate assets are insufficient |
| Third layer: Central Fund | Mutual fund maintained by Lloyd’s Corporation | Serve as a final financial backstop when the first two layers cannot meet liabilities |
The first layer consists of assets and reserves held by each syndicate and managed by its managing agent. These resources are designated to meet claims from insurance contracts underwritten by the relevant syndicate (see Reinsurance Buyers Expect Deeper Property Price Cuts in 2027).
The second layer, Funds at Lloyd’s, comprises additional capital deposited by underwriting members, including corporate participants and individual investors traditionally known as Names.
The amount is determined by each member’s underwriting commitments and calculated using the applicable regulatory capital requirement plus a 35% uplift to provide an additional safety margin.
Funds at Lloyd’s are ring-fenced and available when syndicate resources are insufficient to meet liabilities.
The third layer is the Central Fund, maintained by Lloyd’s Corporation as a mutual financial backstop. The fund may be used to support valid claims when both syndicate assets and the relevant Funds at Lloyd’s have been exhausted.
Annual levies on market participants finance the Central Fund and support its continued operation.
The arrangement provides a common capital security framework while allowing individual syndicates to retain responsibility for their underwriting decisions and financial performance.
Lloyd’s global licensing and international insurance network
Lloyd’s international licensing arrangements provide access to insurance risks across more than 200 jurisdictions. These permissions allow syndicates to participate in international business without establishing separate market-entry arrangements in every territory.
In approximately 80 markets, Lloyd’s has negotiated agreements permitting insurance coverage to be provided directly. The arrangements can reduce administrative costs and regulatory complexity for multinational insurance placements.
For businesses operating across several countries, Lloyd’s multinational capabilities support coordinated insurance programs covering exposures in multiple jurisdictions (see Global Reinsurance Outlook 2027: Softer Pricing, Higher Claims Costs).
A single coordinated arrangement can simplify policy administration, claims servicing and regulatory compliance across borders. This international footprint is supported by the Lloyd’s Global Network, comprising more than 300 agents based in commercial centers and ports. These agents provide local claims assistance, survey services and market intelligence.
Their presence supports underwriting and claims operations in locations where detailed knowledge of local conditions is necessary.
For capital providers, the licensing framework gives access to a geographically diverse range of insurance risks without requiring independent authorization in each market.
Central governance and oversight of the Lloyd’s market
Lloyd’s Corporation provides centralized governance, regulatory oversight and operational infrastructure for the marketplace.
Lloyd’s Corporation oversees market operations and sets regulatory standards, while syndicates and their managing agents handle underwriting and assume insurance risks
Centralized oversight supports compliance with market standards, protection of collective financial resources and coordination of strategic investment.
Conning identifies four strategic priorities within this framework: performance, digitalization, purpose and culture.
The centralized structure allows changes in underwriting processes, technology and governance to be coordinated across participating businesses.
It also distinguishes Lloyd’s from insurance groups whose underwriting operations and capital are managed within a single corporate structure.
Lloyd’s innovation strategy and digital transformation
Innovation has been part of Lloyd’s development since its expansion from marine insurance into motor, aviation, political risk and cyber coverage.
The market continues to develop insurance products for emerging exposures while investing in technology intended to improve underwriting and operational efficiency.
One initiative is Lloyd’s Innovation (ICX) class, which permits syndicates to write an additional 5% of their total annual business plan in innovation-related insurance products.
The arrangement provides underwriting capacity for experimenting with new types of coverage and addressing risks that may not fit established insurance categories.
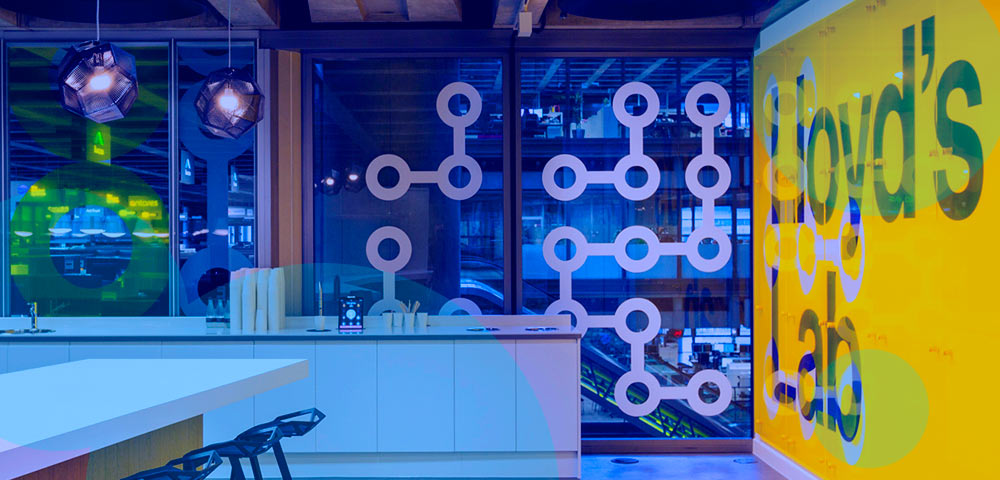
Lloyd’s Lab, the market’s innovation accelerator, supports startups developing technology, data models and processes for insurance applications.
The accelerator provides a route for startups to work with insurance market participants on problems involving underwriting, data analysis and emerging risks. Such initiatives complement Lloyd’s established syndicate structure by allowing specialist underwriting businesses to test new technology and coverage approaches.
Launched in 2018, Lloyd’s Lab has supported more than 150 startups through its InsurTech accelerator. The programme runs two 10-week cohorts annually, typically selecting around ten companies from 150-200 applications.
According to Lloyd’s latest figures for 2026, alumni have collectively raised more than $1.4 bn in investment and generated $426 mn in gross written premium.
Lloyd’s reports that 85% of alumni maintain commercial relationships with the market, while an earlier programme report found that 78% of those relationships originated during the accelerator. Lloyd’s Lab 17th cohort, comprising ten companies, began in September 2026.
Digital placement systems are also becoming more important, supplementing the face-to-face negotiations traditionally associated with the London underwriting room.
Lloyd’s role in global finance and alternative risk transfer
Lloyd’s supports international trade and investment by providing insurance capacity for risks that may otherwise be difficult to finance.
Large infrastructure projects, for example, can require extensive insurance protection before lenders and investors are prepared to commit capital.
Without sufficient insurance capacity, financing costs may increase or projects may become commercially impractical.
Businesses also depend on specialist coverage for exposures such as cyberattacks, supply chain disruptions and other risks that can interrupt operations or create substantial financial liabilities.
Lloyd’s combinated of specialist underwriting, financial security, global licensing and centralized governance as a distinguishing feature. Other insurers may offer comparable expertise in individual classes, while capital markets provide alternative risk transfer arrangements through instruments such as insurance-linked securities (ILS).
Lloyd’s has also developed structures allowing alternative capital providers to participate in its underwriting market.
Its London Bridge 2 platform uses insurance-linked securities transformer vehicles to connect investors with insurance risks written through Lloyd’s.
These arrangements provide ILS investors with access to underwriting exposures while offering an additional mechanism for bringing capital into the market.
The combination of traditional underwriting and alternative capital broadens the sources of funding available for complex insurance risks.
Lloyd’s ability to maintain its international position depends on preserving the strengths of its syndicate model, capital security and specialist expertise while improving technology and operational efficiency.
The market’s continuing role in global risk transfer rests on its capacity to bring together underwriters, brokers and capital providers to insure exposures that individual companies may be unable to accommodate independently.
…………..
Edited by Yana Keller – Re/Insurance Editor at Beinsure