Overview
The global reinsurance market heads into Rendez-Vous de Septembre and the coming renewal season with a broader mix of connected risks. Swiss Re says clients increasingly rely on data, analytics and underwriting expertise to identify new exposures and concentrations across portfolios.
The reinsurer is also developing tailored structures for risks that standard capacity alone doesn’t address. Its approach combines modelling, underwriting knowledge and risk-transfer solutions as clients face higher volatility across property and casualty business.
Demand for protection continues to rise as exposures become more connected. Clients increasingly expect reinsurers to provide technical expertise and data alongside capacity. Swiss Re uses those tools to identify new exposures, assess volatility and support portfolio decisions (see Global Reinsurance Outlook 2027).
Key highlights
- Insured natural catastrophe losses are rising 5-7% annually, with Swiss Re modelling a 2026 peak-loss scenario near $320 bn.
- European insured wildfire losses have increased by an estimated 8-11% a year over recent decades.
- Global data centre investment could exceed $6 tn by 2030, creating an estimated $91 bn insurance premium opportunity.
- Commercial liability losses reached $174 bn in 2025, above the $120 bn recorded for global insured natural catastrophe losses.
- Swiss Re sees growing accumulation risk across catastrophe, AI infrastructure, liability and geopolitical exposures, increasing demand for reinsurance capacity and risk modelling.
Natural catastrophe losses keep reinsurance demand high
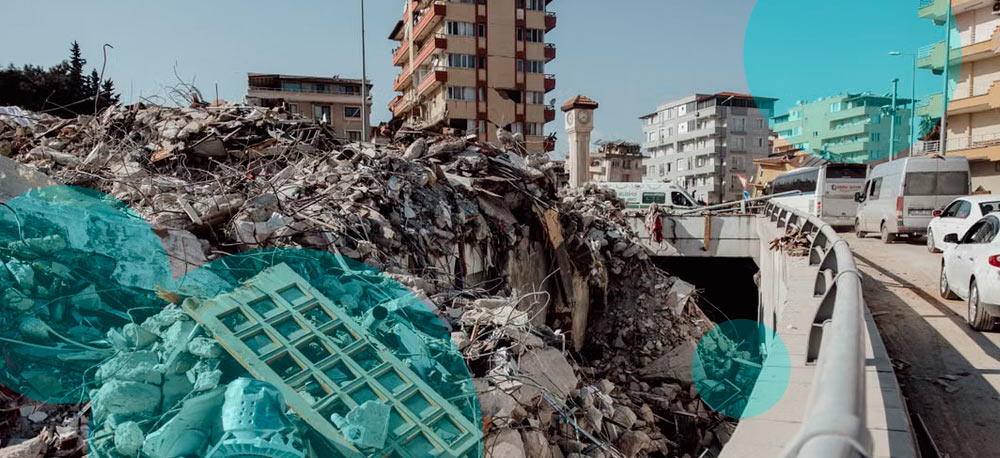
Natural catastrophe risk remains a major source of reinsurance demand. Insured catastrophe losses have been increasing at an annual rate of 5-7%, driven by greater exposure, higher asset values and shifts in hazard patterns.
Swiss Re’s modelling puts a 2026 peak-loss scenario at around $320 bn in insured losses. The estimate shows the scale of protection required for rare events with severe loss potential.
A sequence of hurricanes also creates large annual losses without producing a single record event. Storm clusters similar to Harvey, Irma and Maria in 2017 would push annual insured losses above $120 bn.
| Reinsurance risk indicator | Latest estimate |
| Annual growth in insured natural catastrophe losses | 5-7% |
| Swiss Re 2026 peak-loss scenario | $320 bn |
| Hurricane cluster loss scenario | $120 bn |
| European insured wildfire loss growth (annually) | 8-11% |
| Global data centre investment by 2030 | $6 tn |
| Data centre insurance premium opportunity by 2030 | $91 bn |
| US data centre capacity in significant to very high tornado-day zones | 40% |
| Global commercial liability losses in 2025 | $174 bn |
| Global insured natural catastrophe losses in 2025 | $120 bn |
Europe’s 2026 wildfire season offers another example of changing catastrophe exposure. Swiss Re describes wildfire as the fastest-growing weather peril globally.
Insured wildfire losses in Europe have risen by an estimated 8-11% a year over recent decades. Exposure continues to increase as population and property values expand in wildfire-prone areas.
More detailed data and catastrophe modelling give insurers a clearer view of these exposures. Prevention measures and adaptation efforts also affect how insurers price wildfire risk and structure reinsurance protection.
AI data centre investment expands insurance demand
Global investment in data centres is projected to exceed $6 tn by 2030. Swiss Re Institute estimates the related insurance premium opportunity at $91 bn by the end of the decade.
The US accounts for a large share of that expansion. According to Swiss Re Institute, about 40% of US data centre capacity sits in areas classified as having significant to very high tornado-day exposure.
Larger facilities bring higher insured values and more concentrated losses. Data centres also depend heavily on electricity grids and water supplies.
| Data centre exposure | Insurance relevance |
| Electricity grid dependency | Power disruption could interrupt several facilities |
| Water dependency | Cooling systems create operational exposure |
| Technology supply chains | Component shortages could extend recovery periods |
| Digital infrastructure | Network failures could affect connected operations |
| High asset values | Individual sites could generate large property claims |
| Geographic concentration | One event could affect several insured facilities |
Technology supply chains and digital networks add further points of exposure across individual sites and connected infrastructure.
This concentration creates new underwriting questions for insurers and reinsurers. A single physical event or infrastructure failure might affect several insured operations at once, increasing accumulation risk across portfolios.
US liability losses remain elevated
Commercial liability losses reached $174 bn in 2025. That total exceeded global insured natural catastrophe losses of $120 bn during the same year.
Large court verdicts remain a concern for insurers, while litigation trends continue to create uncertainty around future claims severity. Reinsurers are therefore paying closer attention to claims patterns, legal developments and risk selection.
Pricing discipline also matters more as liability claims become larger and less predictable. Insurers need detailed exposure data to assess where claims inflation and litigation pressure are building.
| Risk area | Main insurance exposure | Reinsurance concern |
| Natural catastrophes | Property damage and business interruption | Higher loss frequency and severe event accumulation |
| Wildfires | Property losses in exposed regions | Rising insured values and expanding development |
| AI data centres | High-value property and infrastructure dependencies | Concentrated losses across connected facilities |
| US liability | Large verdicts and rising claims severity | Pricing uncertainty and claims inflation |
| Geopolitical risk | Higher repair and replacement costs | Supply disruption and correlated portfolio losses |
Geopolitical tensions raise claims costs
Geopolitical tensions add another source of uncertainty for insurers and reinsurers. Disruption across global value chains affects energy prices, commodity costs and industrial supply networks. Those shocks feed into repair and replacement costs. Higher input prices then increase claims severity across property and casualty portfolios.
Insurers also face greater concentration risk when several exposures depend on the same suppliers or transport routes. Understanding those connections has become more important for underwriting and portfolio management.
Underwriting increasingly depends on understanding where exposures interact and where concentrations develop.
Fitch Ratings has maintained its deteriorating outlook for the global reinsurance sector in 2027 as pricing weakens and claims costs rise. Operating and business conditions are expected to soften from still-sound levels, although reinsurers should retain strong capital positions.
Analysts expect reinsurance prices to decline further in 2027, though at a slower pace than in 2026. Abundant capacity remains the main source of pressure as capital supply continues to exceed demand across the market.
Competition between reinsurers should therefore remain intense, keeping conditions favorable for buyers.
………………
AUTHORS: Urs Baertschi – CEO of Property & Casualty Reinsurance at Swiss Re, Gianfranco Lot – Chief Underwriting Officer for Property & Casualty Reinsurance at Swiss Re