Hugo Insurance, a US insurtech company specializing in flexible auto insurance payments, has expanded its distribution partnerships in 2026 while continuing to focus on drivers seeking affordable liability coverage without large initial payments.
The company, established in 2016, developed its business around a pay-at-your-pace model that allows customers to fund insurance coverage through smaller payments rather than conventional monthly installments.
- Hugo Insurance partnered with Root to offer full-coverage insurance options to eligible customers across 16 states. Bristol West joined its carrier network in Texas and Florida in August.
- Hugo’s current Basic product is a six-month liability policy with flexible payments starting at three to 30 days, depending on eligibility. Full coverage is available through partners rather than directly from Hugo.
- Hugo Insurance Exchange received a C financial strength grade from Weiss Ratings. Regulatory records also show additional auto insurance rate reductions in Arkansas.
Its latest developments include a partnership with Root Insurance, the addition of Bristol West as a carrier partner and further rate adjustments by Hugo Insurance Exchange, its policyholder-owned insurance entity.
These changes broaden the options available through Hugo’s platform, although its directly marketed products remain concentrated on basic automobile liability insurance.
Hugo partners with Root to expand full-coverage options
Hugo and Root (NASDAQ: ROOT) announced a partnership giving eligible Hugo customers access to Root’s full-coverage auto insurance products across 16 states. The arrangement combines Hugo’s digital distribution platform with Root’s personalized insurance pricing technology.
Root serves as an additional option for customers seeking protection beyond state-minimum liability requirements, including coverage for damage to their own vehicles.
“Hugo exists for drivers who’ve been underserved by traditional insurance,” said Seth Rediger, head of distribution at Hugo.
The partnership is significant because Hugo does not currently underwrite or directly offer comprehensive and collision coverage through its Basic product.
Customers can instead explore full-coverage quotes from Root, Bristol West and other participating insurers.
In August 2026, Hugo added Bristol West as a carrier partner in Texas and Florida. The change expanded its carrier relationships beyond existing arrangements with First Acceptance and Hugo Insurance Exchange.
How Hugo’s pay-as-you-go insurance works
Hugo’s current Basic plan provides a standard six-month liability insurance policy with flexible payment arrangements.
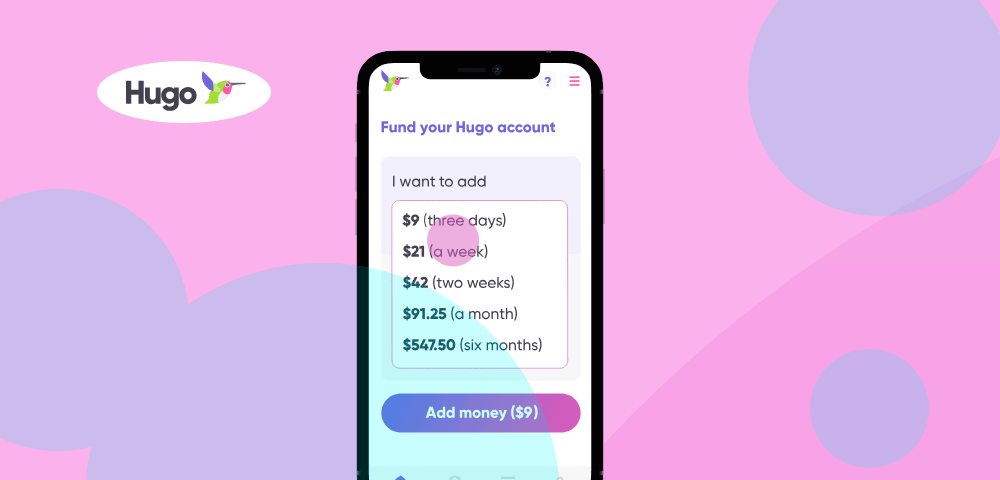
Customers can initially purchase three, seven, 14 or 30 days of coverage, depending on eligibility and state requirements. Additional funds can be deposited manually or through automatic account reloads.
Hugo calculates payments using a daily rate, allowing customers to manage smaller insurance expenses without making a substantial advance payment.
The distinction between flexible payments and insurance coverage is important.
Hugo permits customers to request policy cancellation when they cannot continue paying. However, cancellation creates an insurance lapse that must be reported to the relevant state authorities.
Drivers could face registration penalties or other consequences if they cancel coverage without maintaining insurance required by state law.
Hugo also offers temporary coverage extensions for eligible customers experiencing payment difficulties. These arrangements allow coverage to continue for a limited period, with outstanding daily premiums payable afterward.
The provisions differ by state. South Carolina, for example, has specific cancellation restrictions and grace-period requirements.
Insurance coverage options and limitations
Hugo’s Basic policy provides liability protection meeting applicable state minimum requirements. Depending on the policy, additional medical and accidental death benefits may be available.
The company does not currently offer comprehensive, collision, towing, roadside assistance or rental car coverage directly under its Basic product. It also does not provide SR-22 filings.
This limits its suitability for motorists who need protection against theft, vehicle damage or other losses not covered by third-party liability insurance.
Customers seeking broader protection can obtain quotes through Hugo’s carrier partnerships, but the resulting coverage, pricing and claims arrangements depend on the actual insurer.
Claims are generally handled by the underwriting carrier rather than Hugo Insurance Services. Customers access their carrier’s claims department through the Hugo account.
The company operates primarily through its website and online account management tools rather than a native mobile application.
Hugo Insurance Exchange expands its operations
Hugo Insurance Exchange (HEX), established in 2024, operates as a reciprocal insurance exchange managed by Hugo Insurance Services LLC.
Unlike a conventional shareholder-owned insurer, HEX is owned by its policyholder subscribers, whose interests are represented through a Subscribers’ Advisory Committee.
The exchange lists licenses in Alabama, Arkansas, Kentucky, Louisiana, Mississippi, North Carolina and Tennessee. Licensing does not necessarily mean policies are actively available to every applicant in those states.
HEX policyholders also pay a subscriber contribution, typically equivalent to 10% of premium, which forms part of the overall insurance price.
Regulatory filings show that HEX has continued adjusting rates.
- In Arkansas, the exchange filed for a 16.8% auto insurance rate reduction in May 2025 and a further 12.4% decrease in September 2025. Another filing dated March 19, 2026, recorded a 1.35% decrease.
- In Mississippi, regulatory records show a 19.2% rate reduction filed in September 2025, with implementation dates beginning in October and November of that year.
These figures relate to specific insurance programmes and jurisdictions, not a nationwide reduction in Hugo premiums.
Financial strength and customer satisfaction
Weiss Ratings assigned Hugo Insurance Exchange a C grade in June 2026. The rating agency reported approximately $9.45 mn in assets, $5.43 mn in capital and $2.90 mn in net premiums.
Its assessment identified limited diversification, rapid premium growth and weaknesses in operational stability, while recording stronger liquidity and capitalization measures.
The assessment applies specifically to Hugo Insurance Exchange, not to independent insurance companies distributing products through Hugo.
For consumer satisfaction, Hugo reports that 89% of its Trustpilot reviewers rated the company Excellent, based on approximately 35,000 reviews referenced on its website in 2026.
Hugo does not have a published J.D. Power customer satisfaction ranking comparable with those available for many larger US automobile insurers.
Is Hugo auto insurance worth considering in 2026?
Hugo’s principal advantage remains payment flexibility. Its daily-rate structure can appeal to drivers managing irregular income or those seeking state-minimum liability insurance without substantial advance payments.
The Root and Bristol West partnerships have broadened access to full-coverage quotes, addressing an important limitation of Hugo’s original offering.
The main drawbacks remain restricted direct coverage options, differences between underwriting carriers and the consequences of interrupting insurance coverage.
Drivers with financed or leased vehicles, or those requiring comprehensive and collision protection, will need to evaluate partner insurance products rather than relying solely on Hugo Basic.
Hugo’s 2026 developments indicate a business increasingly combining flexible payment technology with third-party insurance distribution, supported by its own developing reciprocal insurance exchange.