Wearable Technology & Fitness Devices Changes Insurance
Wearable technology like smart watches and fitness devices are changing the way insurers and insureds interact with data, but where has this revolution come from?
Wearable technology like smart watches and fitness devices are changing the way insurers and insureds interact with data, but where has this revolution come from?

According to Insuramore`s global rankings, the TOP-10 P&C (non-life) insurer groups accounted for 25.3% of total P&C gross direct premiums
Political Violence (Re)Insurance Risks are escalating as the world navigates a succession of crises. Economic and geopolitical shocks have dominated agendas

Fitch Ratings does not expect rating implications for U.S. health insurers from the expiration of Medicaid continuous enrollment

FCA review into ESG benchmarks and noted that these benchmarks are poor, and do not provide sufficient information for users to understand the purpose
The aviation re/insurance market has gone through a turbulent few years, with the impact of the COVID-19 pandemic, geopolitical shocks and macroeconomic challenges
The cyber insurance market has seen significant changes, with the segments within the market being more distinct and nuanced than previously experienced
US property and casualty P&C industry underwriting results are likely to improve in 2024 as premium rates rise significantly in underperforming auto
US property and casualty insurance companies had a median price-to-estimated earnings multiple of 12.1x
High demand for global life insurance and increased worldwide risk awareness sparked by the pandemic have encouraged carriers to personalize solutions
Q1 severe weather insured losses should come in at a range of $7 bn to $9.5 bn of insured severe thunderstorm storm losses from hail

As the world is gearing up for a shift to allow environment-friendly electric vehicles, the changing landscape presents opportunities for the motor insurance industry
Policyholders should contact their insurer to obtain the assistance they need. Many claims-filing services are available via either a mobile app or online

Brokers will continue to be a central part of insurance distribution and insurance companies will continue outsourcing insurance distribution
Indian Insurance market stands at $131 bn. The Indian insurance industry grew at a CAGR of 17% over the last two decades
U.S. homeowners’ insurance is poised to post a statutory underwriting loss for reported results, as insurers continue to face above-average catastrophe losses
Slow underlying growth and inflation are among the biggest challenges facing U.S. auto, home, and business insurers
Climate change is an overarching global threat and a source of financial risk in the Insurance Sector, according to recent report, the United Nations
Global Insurance Market Report shares the outcome of the Global Monitoring Exercise, the International Association of Insurance Supervisors’ (IAIS’) risk assessment framework
IFRS 17 requirements could result in accounting mismatches and volatilities in profit and loss—a direct consequence of the insurer’s reinsurance management strategy entered
The natural disasters demonstrate that economic factors, in the last two years augmented by inflation, are the main driver of elevated insured losses from natural catastrophes
Natural disasters resulted in global economic losses of USD 275 billion, of which USD 125 billion were covered by insurance, the fourth highest one-year total
Casualty insurance has seen a decline in coverage and pricing in the 2023, with both of them presenting potential challenges to the insurance market
The US P&C industry recorded a net underwriting loss of $26.5 billion, worsening by $21.5 billion from the previous year
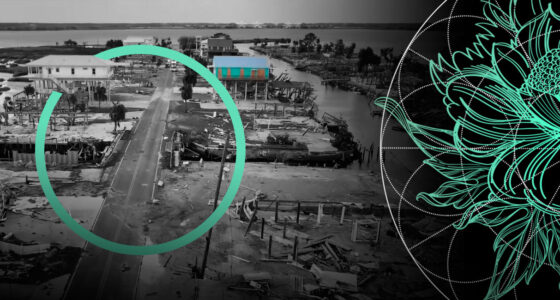
Natural disasters resulted in global economic losses of USD 275 billion, of which USD 125 billion were covered by insurance

While the idea of full-funnel marketing in Insurance has been around for years, most insurers unable to overcome technological barriers
Insurers received a boost from hardening property-casualty rates, but the growth outlook for the insurance sector in the 2024 appears to be a mixed bag
Belgian and Dutch insurers’ conservative investment portfolios should be resilient to rising credit risks amid weakening economic conditions and tightening monetary policy
The increase in interest rates over the last year has been positive for life insurers in Europe, improving both solvency and financial results
Insurers’ investments to the failed banks (Silicon Valley Bank, Silvergate and Signature Bank) are modest. Fitch-rated insurance entities’ direct investment exposure
No Life & Health (L&H) insurance market is fully inclusive. This is supported by the findings of Swiss Re Institute L&H Insurance Inclusion Radar
The US P&C insurance industry has experienced challenges in recent years due, in large part, to increases in the frequency and severity of natural catastrophes
The UK life insurance market will continue to maintain strong capitalisation despite the government’s proposals to loosen Solvency II (S2) rules to release capital for insurers
Natural catastrophe-related losses will continue to be the largest risk to Japanese nonlife insurers’ earnings in fiscal year 2023, though the effects of inflation are catching up

U.S. life insurers’ commercial mortgage fundamentals have largely recovered since the pandemic. TOP 20 Largest Life Insurance Companies
Climate risk has once again been the catalyst for insurance and reinsurance market change. Major losses caused by extreme weather events in recent years
The phenomenon of social inflation has garnered a great deal of attention in the property and casualty (P&C) insurance industry
Following are five D&O mega trends companies should watch for and guard against in 2022, according to AGCS financial lines and D&O experts
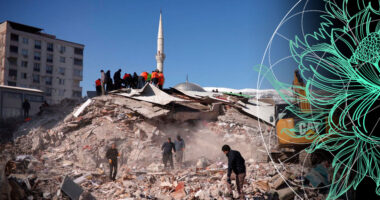
The estimated insurance claims bill from the sequence of earthquakes that hit Turkey and Syria earlier in February appears to be growing

As per GlobalDatas’s Property Insurance Industry Outlook in Asia-Pacific in report, the global property insurance industry recorded a CAGR of 4.1%
Usage-based auto insurance programs have seen a dramatic increase, according to a new report, the consumer data
Global commercial property and casualty (P&C) insurance lines have delivered strong financial performance in recent years following the soft market of 2013 to 2018
Floods affect more people across the globe than any other natural disaster. The deadly floods within year were a tragic reminder of the increasing threat
2024 will be a difficult year for the US P&C industry: claims severities surged with inflation, natural catastrophe losses were elevated for a sixth straight year
Property insurance growth in Europe recovered at 3.2% as compared to a flat growth due to premium price hardening owing to escalating natural catastrophe losses
M&A market activity continued to exceed historical norms while retreating from the new heights of the previous year
The metaverse was already worth nearly $500 bn. That figure is expected to rise to a staggering $800 bn by 2026 as more platforms enter the market
Pricing cycles in the commercial insurance and reinsurance sectors are now converging, marked by price increase moderation overall for the former
Mantissa Group initiated a survey, conducted across life Insurance technology and business leaders, and supplemented by a series of interviews
Legacy technology systems have long been a problem for insurance providers. The idea of moving customer data away from incumbent systems is a daunting prospect for most insurers
The jury ruled in Depp’s favor, and Heard was ordered to pay $8.3 million. Heard then looked to her insurance company to pay the judgment
The “key focus” will be on how high reinsurance costs will impact their operating margins and how much risk exposure they keep on their own balance sheets
Worries about capital and adverse variable investment income are expected to be the focal points of discussion as life insurers report
Climate change is taking an increasing toll. The natural disaster figures are dominated by events that are more intense or are occurring more frequently
According to Global InsurTech Report, 2022 has been a year of macro-realism (for many InsurTechs, investors and risk partners), micro company hardship
The aviation, marine and cargo transit (MAT) Global Insurance Industry is estimated to grow at a compound annual growth rate of 6.4% from 2023-2026

U.S. Property & Casualty (P&C) insurers should see stabilizing to modestly better industry operating performance
The impact of current high inflation on German insurance market profitability should be limited due to their ability to adjust prices
Every insurer should closely monitor price developments, focusing on the drivers relevant to the respective insurance coverages, such as repair costs, construction prices or medical inflation
The immediate impact of inflation on non-life (P&C and health) insurers’ earnings is negative, primarily through rising future claims costs on current insurance policies